Accounting and Reporting in times of Uncertainties

Sherwin Longasa

Manager, Technical Accounting

Accounting and Reporting in times of Uncertainties
https://scrubbed.net/businesses/risk-advisory/Since 2020, the world has been rocked by a series of challenges, including the COVID-19 pandemic, Ukraine-Russia geopolitical tension, rising inflation and interest rates, and a looming recession (collectively referred to herein as “uncertainties”). The uncertainties have severely impacted asset valuation, slowed growth and expansion, challenged liquidity, and led to revenue losses, receivable collection losses, and increased operating expenses, mainly influenced by higher inflation. 
As the negative trend in most entities’ bottom lines continues, profitability ratios are also declining. This can lead to significant fluctuations in critical financial metrics like the current ratio, quick ratio, debt-to-equity ratio, and others, which serve as the foundation for financial covenants. As a result, it is imperative to generate a standard-compliant financial report that accurately reflects the current state of affairs. This report will be crucial for stakeholders, especially creditors and investors, to make informed decisions about their involvement with the business.
The economic upheaval caused by uncertainties has hit businesses of all sizes hard, resulting in some being forced to liquidate or close permanently. As we strive towards recovery, those who managed to survive are still facing the possibility of shutdown and have doubts about their ability to continue operations. These survivors are now faced with the additional challenge of addressing accounting concerns to meet the stringent requirements of US GAAP and other regulatory bodies. Providing accurate and reliable business reports during these uncertain times is essential to ensure compliance and meet stakeholder expectations.
Management should consider the following guide questions in assessing the financial statement impact of uncertainties:
  • How does the entity consider a significant decline in customers’ ability to make payments in their revenue assessment?

Probability of collection
To recognize revenue, ASC 606, Revenue from Contracts with Customers, requires that collection of substantially all of the consideration must be probable. Therefore, even after revenue is recognized at contract inception, the entity shall reassess if there is an indication of a significant change in facts and circumstances. For example, suppose a customer’s ability to pay the consideration deteriorates significantly; the entity shall reassess whether it is probable that it will collect future consideration for the remaining goods and services that will transfer. If the decline in the customer’s ability to make payments occurs subsequently after the entity recognized revenue, an assessment should be made on possible impairment of receivable (you may refer to the CECL discussion below). Further, before assessing collectability, entities must also consider price concessions they may offer customers as it reduces the transaction price.
Contract modification and termination
As challenges continue affecting businesses, some customers may resort to modifying or terminating an existing contract. A contract modification is defined as a change in the scope, price, or both. The entity shall assess whether a contract modification shall be accounted for as a separate contract, as it requires different accounting treatment. A modification is accounted for as a separate contract if there is an addition of distinct promised goods or services for an amount equivalent to its standalone selling price. The partial or complete termination of a contract will typically be accounted for as a modification, as it is a change to the scope and price of the contract.
The deterioration of a customer’s ability to pay and contract modification or termination arising from uncertainties typically will reduce the revenue to be recognized.
  • Does the entity consider relevant information in its estimate of the Current expected credit loss (CECL) for its financial assets?

When developing an estimate of ECL, the CECL model requires consideration of reasonable and supportable information about past events, current conditions, and forecasts of future economic conditions. Entities shall consider how the ripple effects of uncertainties, coupled with volatilities in macroeconomic variables, affect their assessment of ECL. 
Entities are expected to recognize a relatively higher allowance for credit losses during the periods affected.
Also read: CECL Adoption Is Just Around the Corner – Is Your Business Ready?
  • Does the entity perform the ‘lower of cost or net realizable value test in their inventories?

ASC 330, Inventory, requires an inventory initially measured using FIFO or average costing method to be subsequently measured at the lower of cost or net realizable value. Net realizable value is calculated by subtracting the estimated completion, disposal, and transportation costs from the estimated inventory selling price. 
The uncertainties caused widespread supply chain disruption, production stoppage, and inventory damage. It also increased materials, freight, handling, and storage costs, which means higher capitalizable and selling costs. Additionally, selling prices may be lower arising from price concessions granted to customers and a significant decline in demand for the product or service. These are some of the indicators that the net realizable value of the inventory will be lower than its cost, prompting recognition of a loss on inventory obsolescence.  
  • Are there events or changes in circumstances indicating that fixed assets are impaired?

Long-lived assets and finite-lived intangible assets (fixed assets) shall be tested for recoverability per ASC 360, Property, Plant, and Equipment, whenever events or changes in circumstances indicate that its carrying amount may not be recoverable. In addition, the recoverability test follows a review of depreciation estimates and methods.
Supply chain disruption and stoppage of production render facilities and production equipment abandoned or idle. In addition, armed conflicts cripple businesses’ assets. These are circumstances that may necessitate impairment testing and accounting estimate reconsideration. When further testing indicates that the carrying amount of fixed asset is not recoverable, entities shall record an impairment loss. Also, it is plausible that the estimated remaining useful life of the asset will be shortened.
  • Are there events or changes in circumstances indicating that indefinitely-lived intangible assets are impaired?

Evaluating the impairment of indefinitely-lived intangible assets usually involves a two-part test. ASC 350, Intangibles—Goodwill and Other, provides for a qualitative test to assess whether it is more likely than not that the asset is impaired but provides an option to go straight to a quantitative test consisting of a comparison of the fair value of the asset with its carrying amount.
Discounted cash flow is one of the most traditional and standard methods of estimating the fair value of an asset. When the general market condition is unpredictable, entities using this method shall be prudent in their revenue and cash flow forecasts and consider how rising interest rates brings the present value factor used in discounting down.
  • Is there a possibility of a debt covenant violation?

Some long-term debts require compliance with certain covenants. For example, a note payable may include a financial covenant to maintain a minimum current ratio that, when violated, will make the note due and demandable. Even if the lender waives its call right due to the covenant violation for a period greater than one year while retaining future covenant requirements, the debt will not automatically classify as non-current when the covenant is breached. It will be classified as current if the borrower will not be able to comply with the covenant within the next 12 months from the balance sheet date.
If a debt covenant violation happens or is expected after the balance sheet date, the debt will generally be classified as non-current. Still, disclosure of the fact is required in the current reporting period.
  • How do uncertainties impact the probability of recognizing losses on contingencies?

ASC 450, Loss Contingencies defines loss contingency as an existing condition, situation, or set of circumstances involving uncertainty as to possible loss to an entity that will ultimately be resolved when one or more future events occur or fail. Accrual and disclosure of a loss contingency are required when (1) the occurrence of one or more future events confirming the fact of the loss is probable and (2) the amount of loss can be reasonably estimated. ASC 450 does not define “probable,” but is generally considered 75% or more.
Economic instability brought about by uncertainties may cause entities to recognize contingency losses such as those relating to the collectability of receivables, loss or damages of properties and other assets, and product warranties. Accordingly, entities shall be critical in assessing losses as it is a matter of judgment.
  • Does the entity consider events and transactions occurring after the balance sheet date?

Subsequent events consist of those events and transactions that provide evidence about conditions that (a) existed at the balance sheet date (i.e., recognized subsequent events) or (b) did not exist at the balance sheet date but arose after that date (i.e., non-recognized subsequent events).
The subsequent impacts of uncertainties cannot be predicted — effects may linger for some entities, but some might get alleviated. Therefore, entities shall consider which subsequent events would entail adjustments in the financial statements. Examples of these events include the bankruptcy of a customer occurring after the balance sheet date that confirms a bad debt existed at the balance sheet date or sales of inventory after the balance sheet date that give evidence about their net realizable value at the balance sheet date.
  • Does the entity assess the entity’s ability to continue as a going concern?

ASC 205-40, Presentation of Financial Statements – Going Concern requires management to evaluate, annually and for each interim reporting period, whether there are conditions and events that raise substantial doubt about the entity’s ability to continue as a going concern within one year after the financial statements are issued. When substantial doubt about the entity’s ability to continue as a going concern is raised, management shall implement an effective plan of action to alleviate the substantial doubt.
When substantial doubt is raised, regardless if management plans alleviate it or not, the entity shall disclose the principal conditions or events that raised the substantial doubt, management’s evaluation of those conditions or events, and the details of the plan that alleviated (or were intended to mitigate) those conditions or events. Additionally, if substantial doubt still exists after considering management’s plans, the entity shall include a statement in its notes to financial statements indicating that there is substantial doubt about the entity’s ability to continue as a going concern.
Management must perform a going concern assessment as regulators are aware that entities are vulnerable to liquidity risks during this period.
  • Does the company have safeguards to mitigate the increased risk of fraudulent financial reporting due to pressure to meet targets and other key performance indicators?

It is logical to expect a rise in the risk of fraudulent financial reporting during these times of economic uncertainty. Certain stakeholder expectations and incentives tied to a financial metric put pressure on management to commit such fraud in the form of revenue falsification and expense understatement. Entities shall put adequate and effective controls in place to prevent this kind of fraud. Examples of these controls include strictly implementing segregation of duties, performing regular account reconciliations, and promoting a culture of integrity and open communication. These practices are especially vital in nonprofit financial reporting, where transparency and trust are crucial for donor confidence and regulatory compliance, as well as broader risk and SOX compliance requirements.
Note that the set of foregoing questions is not an exhaustive list of considerations, and management needs to conduct a thorough company-wide assessment of all significant accounting considerations. Take Action! To effectively assess the impact of uncertainties, entities must gather information from across the organization and collaborate closely. It’s crucial for individuals within the organization to have a solid understanding of the provisions of US GAAP, IFRS, or other relevant reporting frameworks. Utilizing a financial statement disclosure checklist can help ensure that all required disclosures are complete and accurate. In addition, management should carefully analyze financial statements and look for any unusual or suspicious activity. Seeking guidance from technical accounting consultants or other experts can be helpful in addressing complex accounting issues and ensuring compliance with regulations. By taking these steps, entities can be better equipped to navigate the challenges posed by uncertain economic conditions. How Scrubbed Can Help Analyzing the consequences of uncertainties, from sifting through mountains of data to measuring their impact, can be an arduous process. However, generating precise and pertinent business reports is crucial in contributing to a united global recovery, despite the added workload. Fortunately, Scrubbed offers the expertise of trained professionals who can guide businesses through the intricate accounting and disclosure obligations of US GAAP and other relevant regulatory frameworks. This will enable informed business decision-making and facilitate successful navigation through uncertain times. Contact Scrubbed to learn how we can help in your goal of providing relevant and accurate financial statements in times of uncertainty.
Related Content

Blogs

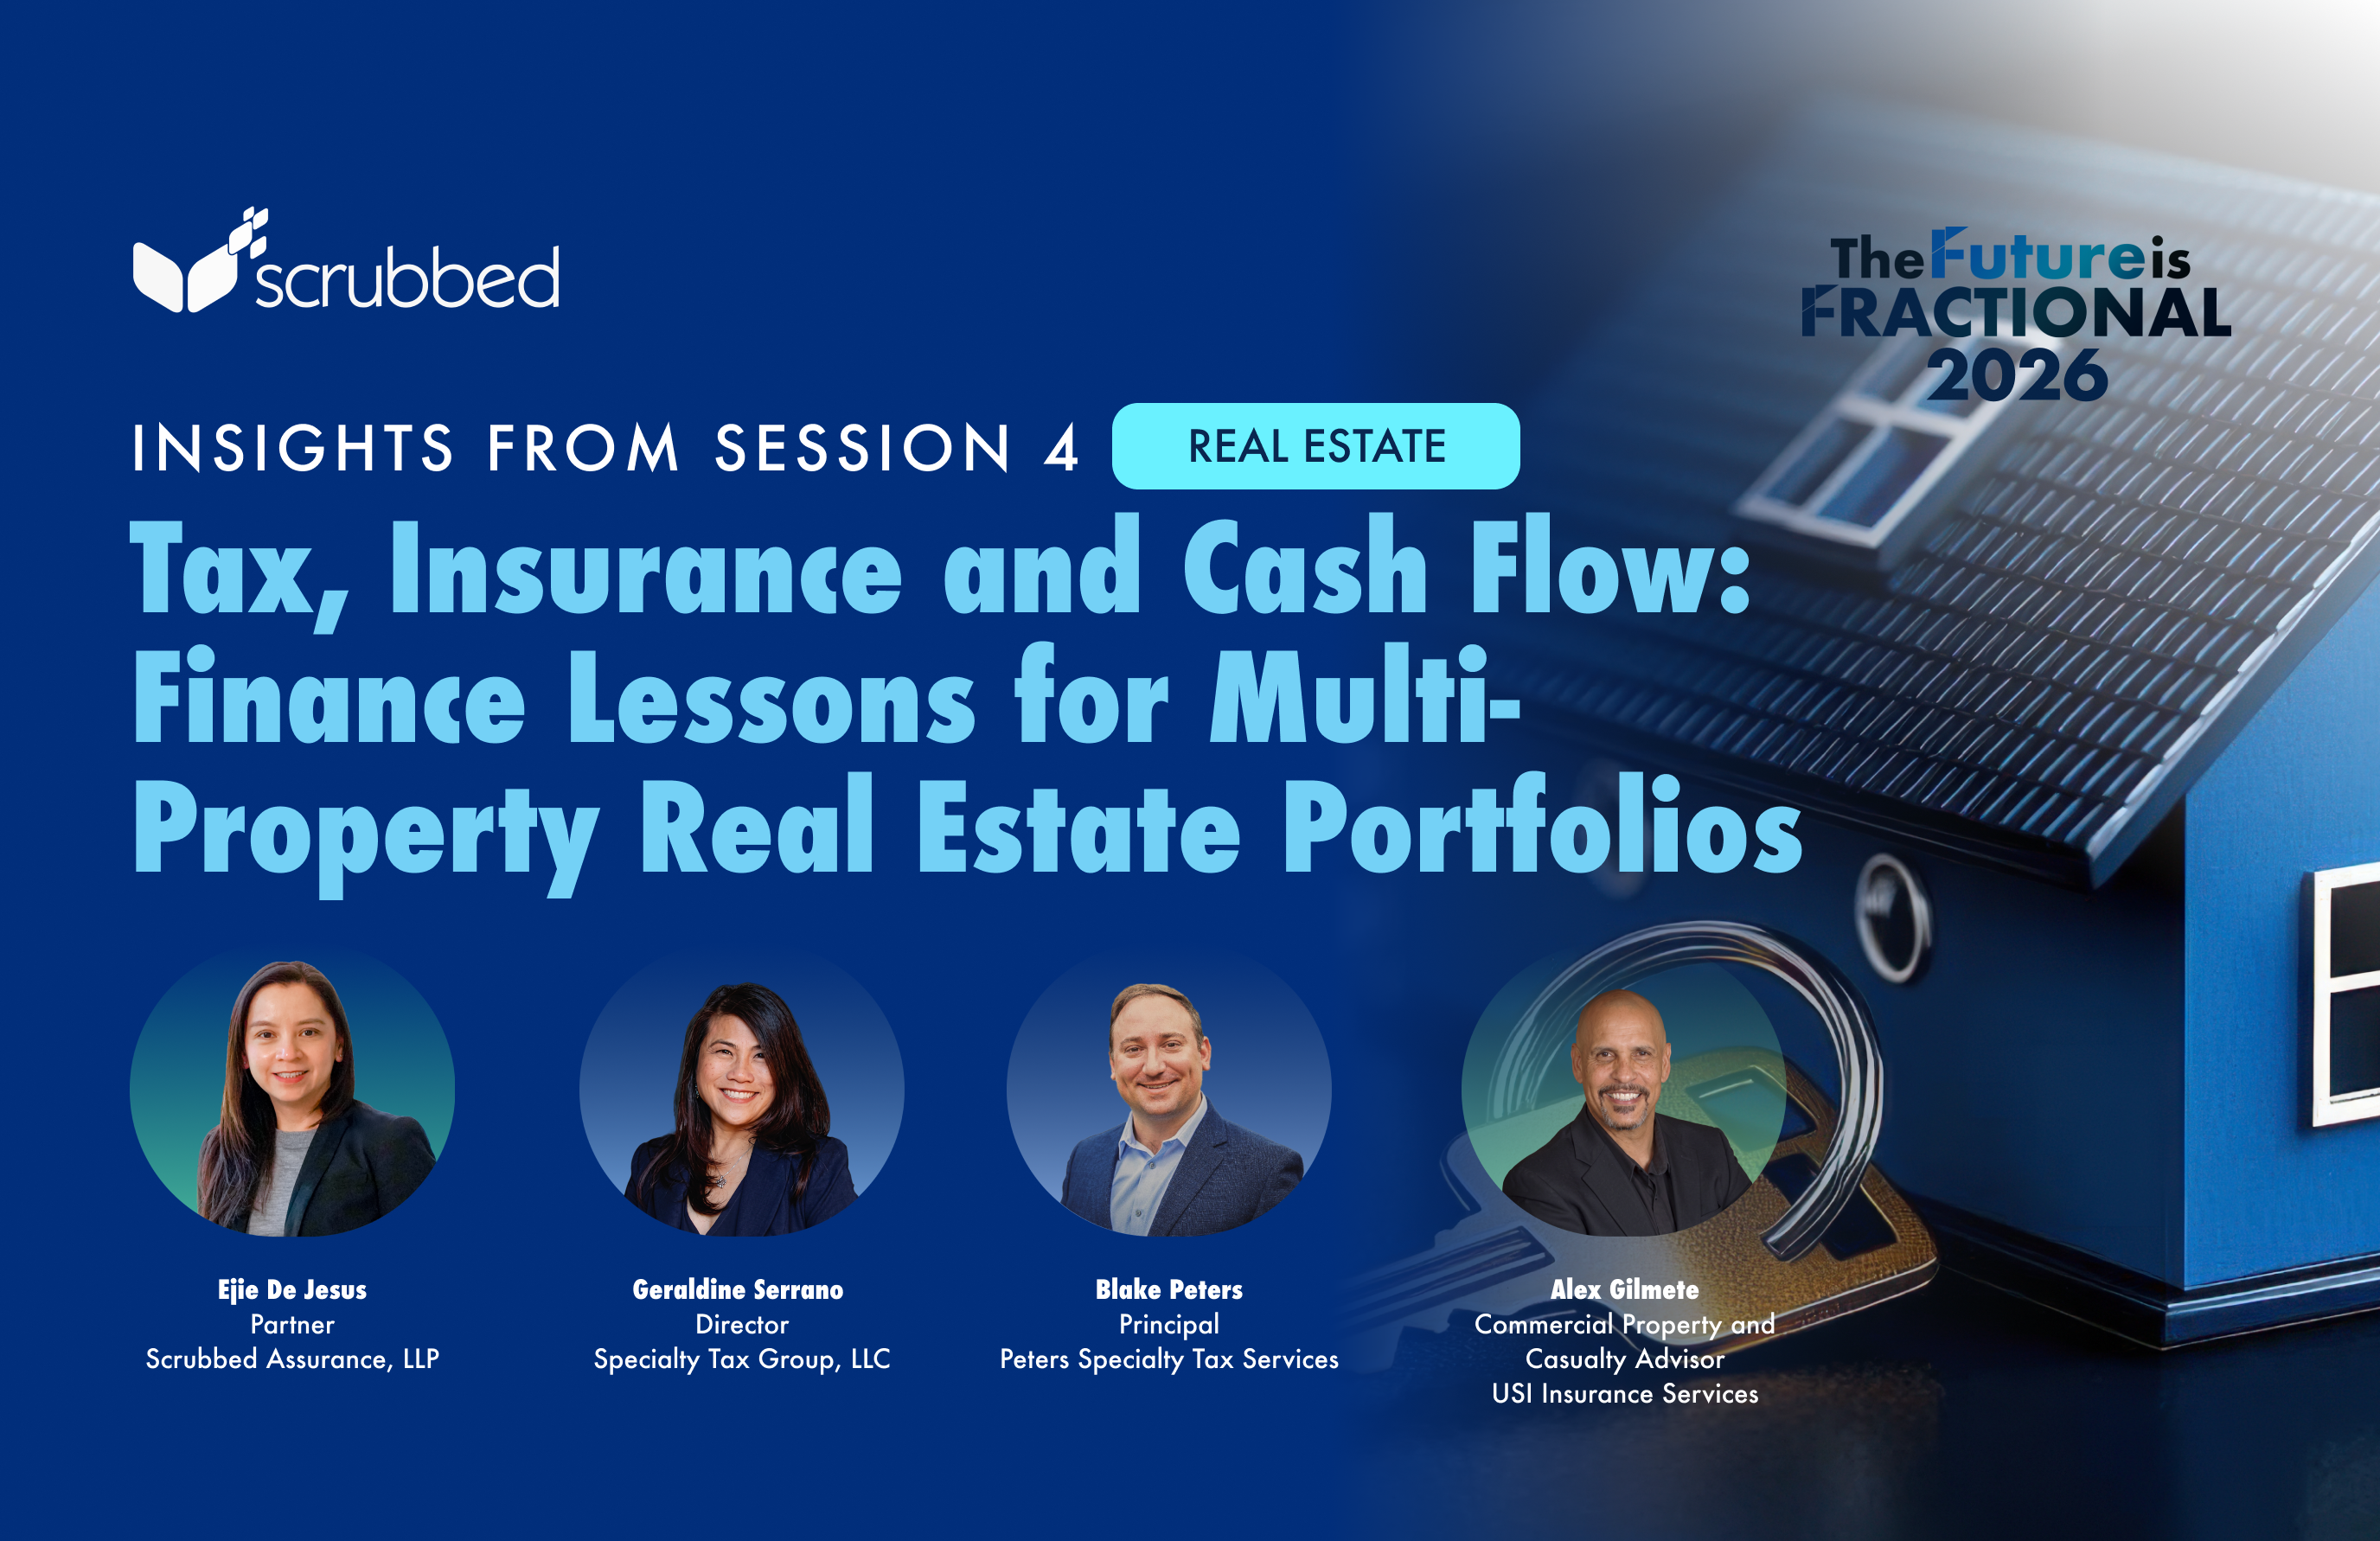
Tax, Insurance and Cash Flow: Finance Lessons for Multi-Property Real Estate Portfolios

Tax, Insurance and Cash Flow: Finance Lessons for Multi-Property Real Estate Portfolios

The Real Estate Spotlight was one of three industry spotlights at The Future Is Fractional 2026, hosted by Scrubbed on September 24, 2026. Scrubbed partner Ejie De Jesus moderated a conversation with Geraldine Serrano, Director at Specialty Tax Group; Alex Gilmete, commercial property and casualty advisor at USI Insurance Services; and Blake Peters, founder and principal of Peters Specialty Tax Services. They covered cost segregation and bonus depreciation, R&D tax credits for real estate, insurance availability and replacement costs, and shared and layered coverage for portfolios. The short version: bring tax and insurance specialists in before decisions are made, check that your coverage reflects today’s replacement costs, and look beyond a general CPA for specialized incentives. Real estate finance is rarely one entity with one set of books. It’s multiple properties, multiple entities and often multiple jurisdictions, in a tax and risk landscape that keeps shifting. At The Future Is Fractional 2026, a virtual conference hosted by finance and accounting advisory firm Scrubbed on September 24, 2026, Session 4 split into three industry breakouts running at the same time: real estate, nonprofit and technology. In the real estate track, Scrubbed partner Ejie De Jesus brought together three specialists in cost segregation, tax incentives and commercial insurance to talk about the strategies owners most often miss. Key Takeaways: Timing is the biggest gap. Tax incentives and cost segregation are often considered after key decisions are made, when the options have already narrowed. Cost segregation accelerates depreciation. Splitting a building into shorter-lived components lets owners take larger deductions sooner, and 100% bonus depreciation, restored by 2025 tax law, can pull those deductions into year one. R&D credits reach further than most owners think. Engineering, structural and energy design work on a property may qualify. Insurance has changed fast. Some properties can’t get standard A-rated coverage, and replacement costs may have outrun policy limits. Portfolios can share coverage. A shared primary layer with excess layers on top can cost less than insuring every property to full value. Bring in specialists early, keep the decisions. Specialist advisors fill in the picture; the owner makes the call. Meet the Panel Ejie De Jesus (moderator): Partner, Scrubbed. Geraldine Serrano: Director, Specialty Tax Group, known as the “Cost Seg Queen,” specializing in cost segregation and tax strategy for real estate investors.  Alex Gilmete : Commercial Property and Casualty Advisor, USI Insurance Services, helping businesses manage and transfer risk.  Blake Peters : Founder and Principal, Peters Specialty Tax Services, specializing in R&D tax credits and other incentive programs. Timing and Visibility Gaps in Portfolio Finance Awareness comes too late. Blake Peters said the largest gap he sees is awareness. Incentives such as investment tax credits, R&D credits and energy efficiency deductions are buried in the tax code, and when owners do know about them, they’re often “looked at a little too late in the process.” Evaluating them at the start of a project can improve returns, help finance it and give investors clearer visibility. Risk has shifted fast.  Alex Gilmete said insurance has changed dramatically in just a few years. Supply chain issues, tariffs and, in California, wildfire risk have reshaped how carriers, lenders and investors view a property, and how much liability an owner carries. Property risk and insurance volatility Standard carriers, non-admitted carriers and the FAIR Plan Some properties can no longer be insured by standard A-rated carriers, Gilmete said. Location, fire exposure and crime all affect what carriers will take on. Coverage Route What The Panel Described   Standard A-rated carriers Increasingly selective; may decline older or un-upgraded buildings   Non-admitted carriers An option when standard carriers decline, at higher cost   California FAIR Plan A fallback in California when other options aren’t available That’s why Gilmete talks with investors while they’re still comparing properties. What a carrier thinks of a location affects rates and coinsurance terms (the clause that penalizes owners who insure for less than full value). He said many investors are looking at Nevada as an alternative to California, while Texas carries its own fire and flood challenges. Are you really fully insured? Gilmete warned that long-time investors may not realize how tariffs and supply chain costs have raised replacement values. A building insured for $10 million might now cost $14 million to $15 million to rebuild after a total loss, leaving the owner to cover the gap. Shared and layered coverage for portfolios Rising premiums reduce net operating income, and lower NOI lowers property value. For portfolios, Gilmete described a shared and layered approach. Take 10 properties worth $10 million each. The owner may not need $100 million of primary coverage, since a total loss on every property in one policy period is unlikely unless they share a fire or flood zone. Instead, a shared primary layer, perhaps $30 million, covers all 10, with excess layers stacked on top from different carriers. Each higher layer is less likely to be used, so it costs less per dollar of coverage. Insurance review checklist, drawn from the panel Does the policy limit reflect today’s replacement cost, not the original value? How old are the roof, HVAC, plumbing and electrical systems, and what fire suppression and egress are in place? Is everything disclosed to the carrier accurate? Carriers may inspect, and can cancel if it isn’t. How do the location’s fire, flood and crime exposure affect which carriers will quote? For a portfolio, would a shared and layered structure fit your risk tolerance? Cost Segregation: Accelerating Depreciation for Cash Flow What is cost segregation? Cost segregation is a tax strategy that separates a building’s components into shorter depreciation periods. Instead of depreciating the whole property over 27.5 years (residential rental) or 39 years (commercial), owners can deduct shorter-lived components faster, lowering current tax liability and increasing cash flow. The Lego analogy Serrano’s explanation: picture a house built of Legos. The IRS treats a residential rental as wearing out over 27.5 years. But not every piece lasts that long. Carpet, floor coverings, cabinets and countertops are five-year pieces. Driveways and landscaping are 15-year pieces. A cost segregation study takes the house apart and sorts the shorter-lived pieces into their own buckets. Bonus depreciation under the One Big Beautiful Bill Act The One Big Beautiful Bill Act, signed in July 2025, restored 100% bonus depreciation and made it permanent for qualifying property acquired after January 19, 2025. Combined with cost segregation, that lets owners deduct the full cost of those shorter-lived components in the first year. Serrano told the story of a client she called “Mr. I Hate the IRS,” who was about to mail a $100,000 check to the IRS. Cost segregation studies on his 12 Denver-area rentals eliminated the liability. His CPA hadn’t recommended it because she believed it applied only to commercial property. Results depend on the owner's situation. Rules on passive rental losses and depreciation recapture when a property is sold can change the math. She also pointed to manufacturers. A newer provision allows qualifying manufacturing buildings to be fully expensed rather than depreciated, so those owners may not need a cost segregation study at all. Before or after construction? Before, Serrano said. “The sooner we talk about the project, the better.” She cited an owner who built an Oakland office from shipping containers and welded them together because it was cheaper. Bolting them, so they could be taken apart, might have qualified far more of the building as five-year property. That may not have changed his choice, but he would have made it knowing the tax impact. He also demolished an existing structure without his CPA setting up a general asset account, and missed a tax benefit as a result. For cost segregation, she noted, what matters is when a building was bought and placed in service, not its age. Insurers look at age. Planning has to account for both. R&D Tax Credits for Real Estate and Construction Peters called the R&D credit “one of the worst named credits out there.” For tax purposes, it can cover work involving analysis, alternatives and design, not just scientists and software. In real estate, that can include: Engineers evaluating structural methods depending on contract terms HVAC and energy design to meet efficiency or LEED requirements Custom engineering to improve a building’s performance Manufacturers building capital-intensive facilities Investment in AI, built in-house or subcontracted, across industries His advice: don’t ask “do we do R&D?” Ask where the money and effort are going. What changed recently. From 2022 through 2024, research expenses had to be spread over five years or more instead of deducted right away, research expenses had to be amortized rather than deducted right away, which made the credit less attractive. Peters said the One Big Beautiful Bill Act fixed that going forward and, for some businesses, retroactively. Companies that stopped claiming the credit should reassess. Cost segregation vs. the R&D tax credit. Header Header R&D Tax Credit What it does Accelerates deductions, which lower taxable income A credit that reduces the tax owed dollar for dollar What can qualify, per the panel Shorter-lived components: flooring, cabinets, countertops, driveways, landscaping Structural engineering, HVAC and energy design, custom building systems, capital-intensive facilities When to look Before construction or acquisition decisions At the front end of a project Overlap - Custom HVAC and energy work often touch both, so owners can address them together Capital Improvements: Tax benefit and Insurability Do roof or HVAC upgrades lower insurance costs? Not directly, Gilmete said. But major carriers may refuse to quote older buildings that haven’t been upgraded. He described a Santa Clara property where the roof had to be replaced before A-rated carriers would consider it. On the tax side, Peters said custom engineering for HVAC or energy performance can qualify for the R&D credit. Keep the Decisions, Bring in the Experts The panel’s closing advice was about what to keep in-house. General CPAs may be excellent but lack this level of specialization. Serrano offers clients a second review by another CPA when their current CPA is unfamiliar with cost segregation. Bringing in specialists early to review tax incentives, cost segregation, contracts, insurance policies and risk tolerance lets the owner decide with a full picture. As Gilmete put it, the experts “fill out your dashboard, and then the owner gets to make decisions based on that dashboard.” This session is part of TFIF 2026.  To see how planning connects to talent, AI and team design, read, read Own the Core, Access the Rest: What The Future is Fractional (TFIF) 2026 Revealed About How Finance Teams Are Being Rebuilt   what finance leaders are rethinking about talent, AI and team structure.

Read More >
Blogs

Own the Core, Access the Rest: What The Future is Fractional (TFIF) 2026 Revealed About How Finance Teams Are Being Rebuilt

Own the Core, Access the Rest: What The Future is Fractional (TFIF) 2026 Revealed About How Finance Teams Are Being Rebuilt

The Future Is Fractional (TFIF) 2026 was a virtual conference hosted by Scrubbed on September 24, 2026. The program included an opening keynote, three panels, three industry spotlights on real estate, nonprofit and technology, and a closing conversation on building a finance team. Sixteen speakers and seven moderators took part, including CEOs, CFOs, fractional finance leaders, AI practitioners, and tax and insurance specialists. The day’s core idea came from Scrubbed CEO Vince De Leon : “Own what is core. Get access to the rest.” This article draws together the themes that ran across sessions: finance team structure, AI and human accountability, data and process foundations, permanent readiness, and early information and cash. It’s written for CFOs, controllers, CEOs and founders deciding how to structure their finance function. For decades, building a finance function followed a simple rule. Need a capability, hire someone. Need more capacity, add headcount. Need deeper expertise, hire a specialist. That rule is under strain. Strong controllers and technical accountants are still hard to find. AI can now do real work inside accounting roles. And demand on finance teams rises and falls with closes, audits, fundraising, acquisitions and downturns, while the payroll behind them stays fixed. Those pressures ran through every conversation at The Future Is Fractional (TFIF) 2026 , a virtual conference hosted on September 24, 2026, by Scrubbed, a professional services firm providing accounting, finance, and tax solutions. The event brought together CEOs, CFOs, fractional finance leaders, AI practitioners, and industry specialists across technology, non-profit, and real estate The speakers came from different seats, and they didn’t always agree. But the same three questions kept surfacing: What should a finance team own? What can it reliably access? And what still requires a person? Key Takeaways: Capability is separating from headcount. Talent scarcity, AI and uneven demand are pushing leaders to ask what they need to own and what they can reliably access, rather than who to hire next. Own what depends on context; access what depends on depth or intensity. Roles built on inside knowledge and relationships tend to stay in-house. Specialized or periodic work is a common candidate for fractional or outside support. AI changes the work, not the accountability. Speakers described real gains in coding, extraction, reconciliation review and drafting, and agreed that a named person must review and own the output. Foundations come first. Documented processes and clean, connected data decide how much AI can deliver. Readiness and early information build trust. Audit, fundraising and deal readiness is a standing condition, and boards value being told early over being told precisely. The Bigger Shift: Capability is Coming Apart from Headcount In his opening keynote, Scrubbed CEO Vince De Leon named three forces arriving at once: talent is scarce, AI is here, and demand is becoming more variable. None is new on its own. Together, they weaken the assumption that capability and employment have to be the same thing. His suggested reframe: instead of starting with “Who do we need to hire?”, start with “What capability do we need, and what do we have access to?” Some capabilities belong inside the company. Some are needed only periodically. Others can come from specialists, global teams, fractional leaders or technology. Fractional finance means accessing finance capability, such as a CFO, controller, or specialized accounting expertise, part time or for a specific need instead of through a full time hire. At TFIF 2026, it was framed as separating capability from headcount: owning what is core and accessing the rest. He was careful about what that doesn’t mean. “A bad fractional hire is still a bad hire. A good full-time hire is still valuable.” The standard for judgment, ownership and accountability doesn’t change with the employment model. He left the audience with three questions that the rest of the day kept answering in practice: What capability do I really need to own? What work should no longer require a person? Where am I carrying fixed capacity against variable demand? Finance Team Structure: What to Own and What to Access A hybrid finance team combines in-house staff with outside capability such as fractional leaders, offshore accounting teams, specialists and AI tools. At TFIF 2026, speakers from very different organizations drew the line between the two in similar places. Owned Layer (In-House) Accessed Layer (Fractional, Outsourced or Specialist) What it depends on Inside context, relationships, final accountability Technical depth, periodic intensity, scalable volume Examples raised at TFIF Handling new vendors and unusual charges; grant accounting; reviewing reports; approving AI-assisted work Routine transaction booking; fractional CFO leadership; merger and scaling support; cost segregation, tax credit and insurance expertise Typical role of people Review, interpret, decide Produce, execute, advise The owned layer tends to be about context and relationships. Ottavio Siani , a fractional CFO who also runs an eight-location coffee business, described the split in his own company. His on-site finance person handles anything new, like an unfamiliar vendor or an unusual charge, while an offshore team handles routine booking. The in-house role shifts, in his words, to “You will be reviewing this report. You will not be producing the report.” Costa John , CEO of Chief Assignments, speaking on nonprofit finance, drew the line at the grant accountant, a role built on relationships with program leaders and funders that may not translate if outsourced. He also flagged a common mistake: hiring a fractional CFO for strategic work while the books still don’t close cleanly. The CFO gets pulled back into bookkeeping, which he called “the most expensive way to solve the wrong problem.” The accessed layer tends to be about depth or intensity. Naita Saechao Chialvo , a fractional CFO who works with nonprofits and social enterprises, described keeping a core internal team and flexing in outside expertise for mergers, scaling or strategic initiatives that internal teams, and often budgets, aren’t built for. The real estate panel made the same point about specialists in cost segregation, tax credits and insurance: the experts “fill out your dashboard, and then the owner gets to make decisions.” Stage changes the answer, and speakers read it differently . Thar Casey , CEO of AmberSemi, described a progression from bookkeeper to in-house accountant to fractional CFO once fundraising begins, with in-house leadership eventually needed because investors want institutional knowledge that stays. Others were less sure the flexible layer has to shrink. Marcus Guerro , President of Guerro Enterprises, described an interim placement scoped for two or three months that was still in place five years later. Siani said he had yet to see, at the small and mid-sized companies he works with, a hybrid model that outgrows its third-party resource. The two tend to grow together. Eric Valle , Director of Partnerships at Aduro Advisors, described a lean version of that model: “You don’t need to build an entire finance team, you kind of just need one controller and have that person manage out a team.” The shared conclusion wasn’t that one model wins. It was that team structure is now a decision made capability by capability, rather than a default. The Flexible Layer Only Works When it’s Integrated Access doesn’t come free. Guerro distinguished relationship-based partners from transactional staffing, and firms whose consultants are trained employees with managers behind them from individual contractors working alone. Siani asks prospective accounting partners how many clients each accountant carries (four or five is a good answer; 20 is a warning sign) and whether the team knows his industry. He sets communication rules early and spends the first months showing in-house staff that outside support is there to lighten an overloaded plate, not to replace them. AI in Finance is Changing the Work, and Accountability stays with a Person No session framed AI as a story about eliminating roles. The consistent message was that AI is changing what those roles consist of. The gains described were specific. Dawn Hatch , founding partner and CEO of MATAX, an AI-native accounting firm, pointed to transaction coding at volume, document extraction, first-pass reconciliation review and narrative drafting that gets “about 90% of the way there.” Her less obvious point: AI lets a team review 100% of transactions instead of a sample, so quality improves along with speed. Siani said that across a nine-month engagement rebuilding a client’s finance function, he “didn’t type a single formula into Excel.” He structured and quality-checked the models Claude built instead. The same speakers were blunt about limits. Blaze O’Byrne , co-Founder of Byron, whose company builds AI agents for CPA tax workflows, said the work “shouldn’t be fully handed off to AI today.” Hatch put it more directly: “the reviewer has to own the output, regardless of what is creating the draft.” Siani, who has been hired to clean up after clients adopted tools promising fully automated accounting, advised skepticism toward any such promise. Rusty Canada , co-founder of Ternpoint Solutions, said it “should scare companies” to picture an agent acting in the accounting system without oversight. Session moderator Kendrick Kho , Scrubbed’s Chief AI Officer, added that products branded as an “AI accountant” or “AI chief of staff” can quietly write the human review step out of the process. This connects to a principle De Leon carried from his years as a CTO: “Technology should remove the work. It should not remove the value.” If AI saves three hours and those hours fill with more of the same work, productivity rises. If they go toward understanding the business or making better decisions, the role itself changes. Kho described that shift in accounts payable, where people move from document capture toward vendor work and analysis. AI in Finance is Changing the Work, and Accountability stays with a Person Banning AI tools doesn’t stop their use, Canada noted; it pushes staff toward personal accounts. Kho shared anecdotes of mid-market companies without a ChatGPT business plan discovering 80–90% organic adoption anyway. The practices speakers recommended instead: Practice What It Means Raised By Classify the data, not the tool Tier data as public or anonymized, client-identifying and regulated, so people know what can go where  Hatch Keep an approved tools list with a fast path Vet training terms, retention and sub-processors quickly; slow approvals push people around the rules  Hatch Provide enterprise tools Give staff an enterprise AI account with limited access rather than leaving them to personal ones Canada, O'Byrne Surface Exceptions Route uncertain or unusual items to a person’s attention instead of asking them to recheck everything O'Byrne Name the approver Put a named person on every sign-off, with an audit trail O'Byrne, Hatch Check with a second model Use a separate AI to look for errors in the first one’s output O'Byrne  Run Evaluations Test workflows against known cases, and retest after any model or prompt change Hatch  Go deeper on where AI is delivering measurable ROI in accounting today . The Foundation Comes Before the AI If one idea ran through every AI discussion, it was that AI amplifies whatever it sits on. Hatch said pilots succeed when a documented process exists before the AI arrives and stall when it doesn’t. Otherwise, “you’re just making confusion faster.” Asked how she would spend a hypothetical $500,000 technology budget, she said AI would come last, after core systems, data hygiene and senior reviewers. Skipping those steps, she said, is “buying the faster way to wrong.” Not everyone ordered it that way. O’Byrne’s first move would be to put an enterprise version of ChatGPT or Claude in staff hands, then invest in cybersecurity. Canada would start with the systems stack and outside guidance. The disagreement was about sequence, not about whether the foundation matters. Abdul Wahab Zafar , SVP of Finance at Studycast, made the case from the systems side. Reliable financial data starts upstream: customer, contract and billing data need a common key tying them together. That’s why, in his view, AI makes finance both easier and harder. Reconciliations and reporting get faster, but deeper analysis breaks down when data from different systems doesn’t line up. He also argued that 90–95% data alignment is often more cost-effective than chasing the last 5%. Simplicity was a recurring defense. Zafar urged teams to fully use the systems they already have before buying new ones. Costa John advised growing nonprofits to start with the lightest accounting system that works. Satoshi Steimetz , CFO of Playworks, supplied the counterweight: across 16 regions and 12 departments, a spreadsheet budget is no longer possible. The right system depends on scale. Readiness is a Permanent Operating State Several sessions arrived at the same view of readiness for audits, fundraising, acquisitions and shocks: it’s a standing condition, not a project that starts when a deal appears. Casey described fielding three inbound acquisition inquiries while raising money and knowing his company wasn’t clean enough to respond. His advice: “readiness, readiness, readiness, be ready, always be ready.” Guerro framed the cost. Companies that save a few thousand dollars a year by under-investing in finance can lose millions in valuation when the books aren’t ready for diligence. Asked when a company should start preparing its back office for a possible acquisition, Zafar answered, “as of yesterday.” The real estate panel added a planning version. Blake Peters, founder of Peters Specialty Tax Services, said incentives such as R&D credits and energy efficiency deductions are often “looked at a little too late in the process,” once a project is well underway. Geraldine Serrano, Director of Specialty Tax Group, LLC described an owner-builder who missed tax benefits because the cost segregation conversation happened after construction decisions were made. Alex Gilmete, a commercial property and casualty advisor at USI Insurance Services, warned that a $10 million building could now cost $14 million to $15 million to replace, leaving policies written to old values short. Readiness, in these conversations, wasn’t about perfection. It was about not being surprised by questions that were always going to be asked. Read what mid-market leaders learned redesigning their finance function. Finance earns Trust by Being Early The planning and industry sessions shared a view of what makes finance valuable to leadership. It isn’t precision. It’s timing. Steimetz described a budget miss at Playworks that surfaced in the final quarter of the fiscal year, too late to respond. “The size of the miss mattered less than how late it surfaced.” The organization now reviews revenue weekly, refreshes the full forecast monthly and updates a five-year projection quarterly. His conclusion about boards: “Confidence is not built on being right, it’s built on being early with the information.” Cash was the common measure. Playworks holds enough cash for six months of operating expenses, which Steimetz said lets it absorb bad news and act on opportunities. Costa John suggested every nonprofit board packet show one number: how many days of cash expenses unrestricted, uncommitted reserves can cover. Zafar holds customer payment terms firm while negotiating longer vendor terms, keeping a cushion between cash in and cash out. Information also has to lead somewhere. Danielle Morris, a succession and governance strategist, argued that finance teams need predictive indicators because financial statements are lagging ones. Costa John said boards should get the forward look, its impact, and a range of choices, not a single option to approve or reject. This loops back to structure. A team consumed by closing the books has little time for forward-looking work, which is one reason speakers kept separating compliance capacity from strategic capacity. Explore how finance leaders plan when uncertainty is the baseline. A Diagnostic For Finance Leaders: 8 questions TFIF didn’t produce a universal answer, and its speakers would be the first to say it shouldn’t. Scrubbed CFO Aira Pineda offered a better starting point as she closed Session 1: “You don’t have to build the whole engine yourselves, you just have to know it well enough to know when something’s off, and who to call when it is.” Knowing your function that well starts with a few questions to work through with your team: Where is our finance team stretched? By volume, complexity or timing? Each points to a different fix. Which capabilities depend on the context only an insider has? Those are strong candidates to own. Where are we carrying fixed capacity for variable demand? Think technical accounting during an audit, FP&A during planning, or CFO-level work during a raise. Is our process documented well enough to automate? If not, that’s the first project, before any AI tool.   Who signs off on AI-assisted work, and do they know what they’re checking?   If an acquirer or auditor called tomorrow, would we trust our own data? How early does our board hear about a change in assumptions? If we bring in outside support, how will it work with our team, and who owns that relationship? The Org Chart is Becoming a Design Decision The last generation of finance teams was built by accumulation: a new need, a new hire. TFIF 2026 suggested the next will be built by design. Leaders will decide which capabilities to own, which to access, which work technology should take on, and where a person’s judgment has to stay. That’s harder than hiring by default. It takes knowing your processes well enough to redesign them, your data well enough to trust it, and your business well enough to tell what’s core from what isn’t. The speakers who had done that work described finance functions that held up better under pressure and gave leadership answers sooner. For most finance leaders, the question is no longer whether this shift is coming. It’s which part of their own function to rethink first. Explore the TFIF 2026 conversations Want to go deeper? Each session has its own article: How We Actually Built It (Session 1) : Mid-market leaders on the signs a finance function has outgrown its structure, vetting partners, and the first 90 days of a redesign. AI in the Finance Function (Session 2) : Where AI delivers ROI today, why pilots stall, and a practical governance model for finance teams. Planning Through Permanent Uncertainty (Session 3): Rolling forecasts, scenario planning, cash reserves and keeping board confidence when assumptions shift. Real Estate Spotlight (Session 4): Cost segregation, R&D credits and insurance strategy for multi-property portfolios. Nonprofit Spotlight (Session 4): Liquidity, restricted funds, board reporting and building finance capacity on a tight budget. Technology Spotlight (Session 4): Data integrity, usage-based revenue forecasting, cash flow discipline and M&A readiness. Building Your Finance Team (Session 5): Choosing between in-house and third-party support, vetting a partner, and scaling a hybrid model. Who Spoke at TFIF 2026 Session Moderator Speakers  Keynote: The Future Is Fractional   Vince De Leon, CEO, Scrubbed  Session 1: How We Actually Built It Aira Pineda, CFO, Scrubbed Thar Casey, CEO, AmberSemi; Eric Valle, Director of Partnerships, Aduro Advisors; Marcus Guerro, President, Guerro Enterprises Session 2: AI in the Finance Function  Kendrick Kho, Chief AI Officer Rusty Canada, Partner and Co-founder, Ternpoint Solutions; Dawn Hatch, Founding Partner and CEO, Matax; Blaze O’Byrne, Co-founder, Byron  Session 3: Planning Through Permanent Uncertainty Darwin Pangilinan, Chief Client Officer, Scrubbed  Satoshi Steimetz, CFO, Playworks; Naita Saechao Chialvo, Fractional CFOO and Consultant; Danielle Morris, Founder and Chief Strategist, Triconal   Session 4: Real Estate Spotlight Ejie De Jesus, Partner, Scrubbed Geraldine Serrano, Director, Specialty Tax Group; Alex Gilmete, Commercial Property and Casualty Advisor, USI Insurance Services; Blake Peters, Founder and Principal, Peters Specialty Tax Services Session 4: Nonprofit Spotlight  Laurence Ruelo, Director of Business Development, Scrubbed  Costa John, CAO, CFO Assignments Session 4: Technology Spotlight  Anthony John Rogador, Accounting Advisory Services Manager, Scrubbed Abdul Wahab Zafar, MBA, CMA, SVP of Finance, Studycast Session 5: Building Your Finance Team  Debra Andrews, CMO, Scrubbed Ottavio Siani, Founder, Triangle Coffee, and Fractional CFO The event was hosted by Ruth Angela Dela Cruz and Fran Redoblado.

Read More >
Blogs

September 15 Estimated Tax Deadline: Strategies for Pass-Through Entities

September 15 Estimated Tax Deadline: Strategies for Pass-Through Entities

For growing pass-through entities, the September 15 tax deadline often creates a collision between cash flow and internal capacity. Guessing at estimated payments leaves companies vulnerable to IRS penalties or unnecessarily traps critical working capital meant for Q4 growth. By establishing a Safe Harbor floor and utilizing the Annualized Income Installment Method, companies can align tax outlays directly with actual revenue. When this execution is handled proactively, finance leaders stop playing defense against deadlines and reclaim their time for strategic planning. When a high-growth pass-through entity, such as an S-Corp or a Partnership, comes off an unexpectedly strong summer, revenue is up. This should be a moment for leadership to celebrate and plan their Q4 investments. Instead, the internal finance team often finds themselves staring down a cash crunch they didn't anticipate. The pressure point is September 15. For growing operations, this date is often a collision course. It is not only the deadline for Q3 estimated tax payments, but it is also the extended filing deadline for Forms 1065 and 1120-S . When you have an internal team trying to finalize the previous year's historical data while simultaneously projecting the current year's performance, the structure usually begins to strain. This isn't about a team dropping the ball. It's simply what happens when internal workflows haven't scaled up to match a company's growth. When two major deadlines collide, and the volume is too high, a stretched team has no choice but to improvise. The Cost of "Guesstimating" In a pass-through entity, the business itself generally does not pay federal income tax. Because income from partnerships and S corporations generally passes through to their owners, owners may need to make individual estimated tax payments based in part on their share of the entity’s taxable income When internal teams don't have a dedicated workflow for this, they often get bogged down trying to predict exact year-end profits during a busy quarter. Without a clear mechanism to manage this, I frequently see companies do one of two things: they either underpay and leave themselves vulnerable to IRS penalties, or they overpay to "be safe." Overpaying might feel like the responsible choice in the moment, but it unnecessarily ties up working capital. When these distributions are sized off gross revenue rather than a projection that accounts for deductions or state-level elections, the company pulls more cash out of the operating account than the owners actually owe. That excess traps liquidity that could have been used to fund critical Q4 growth initiatives—like a marketing push or inventory expansion—without seeking outside financing. Establishing an Estimated-Tax Safe Harbor  When our tax professionals step in to manage this process, the very first thing we do is establish a predictable foundation. We immediately build a "Tax Compliance Calendar" integrated with a "Safe Harbor Floor." A useful starting point is determining which estimated-tax safe harbor applies. For many taxpayers, one option is to base required annual payments on 100% of the prior year's tax, increasing to 110% for certain higher-income taxpayers. The current-year 90% test may also apply. Meeting the applicable requirements through timely payments can generally reduce exposure to estimated-tax underpayment penalties. Once that floor is established, we can adjust for the reality of the current year. Aligning Outlays with Actual Cash Flow If a company sees a massive spike in revenue during Q3, the standard installment method might demand a payment that creates a sudden cash flow imbalance. Good intentions won't balance the cash flow at this stage; you need a precise mathematical approach. To stabilize cash flow during a sudden revenue surge, one strategy to consider is the Annualized Income Installment Method . Instead of assuming income is earned evenly throughout the year, the Annualized Income Installment Method determines the owner's required installments based more closely on income earned during the applicable annualization periods State-level PTE tax elections may also provide federal tax benefits by allowing qualifying state income taxes to be paid and deducted at the entity level rather than being subject to the individual SALT deduction limitation. The result? Depending on the state's PTE tax regime, entity-level payments may reduce the state estimated-tax payments otherwise required from individual owners. A deductible PTE tax payment may also reduce the taxable income passed through to owners for federal purposes, which can affect their projected federal estimated-tax liability. Restoring Strategic Headspace When tax planning is handled consistently throughout the year, it changes how a leadership team operates. It can significantly reduce the risk of an "April Surprise." When Q3 estimates are calculated accurately and tied to a deliberate strategy, leadership knows exactly how much capital is truly theirs to spend. Tax shifts from a looming, unpredictable liability into a manageable line item. Just as importantly, the internal finance leader gets their time back. Instead of spending the first two weeks of September finalizing and issuing K-1s, calculating thresholds, and worrying about penalties, they can focus on high-level financial modeling and operational efficiency. A strong tax partner doesn't just run the numbers; they take the friction out of the process so your team can focus forward. When an experienced team handles the heavy lifting behind the scenes, you stop playing defense against IRS deadlines and start using tax strategy as a genuine tool to fund your growth. See how our tax professionals support growing operations and keep execution predictable. Let's talk through how we can support your finance function. Comparing Q3 Tax Strategies: Safe Harbor vs. Annualized Method vs. PTE Strategy Ideal for Primary Benefit Risk Level  100%/110% Safe Harbor  Rapidly growing companies  Provides protection from estimated-tax underpayment penalties when applicable safe-harbor requirements are satisfied  Low (May temporarily tie up cash if revenue drops)  Annualized Method  Seasonal or late-year spiking revenue Align tax outlays directly with timing of taxable income  Moderate (Requires meticulous record-keeping) PTE Tax Election Entities in high-tax states May provide an entity-level federal deduction for qualifying state income taxes while providing state tax benefits to eligible owners Low (Requires state-specific eligibility and election compliance) Key Takeaways: The Deadline Collision: The simultaneous timing of Q3 estimates and extended historical filings places severe strain on internal finance teams when workflows haven't scaled. The Cost of "Guesstimating": Overpaying estimated taxes based on gross revenue ties up liquidity that could otherwise fund critical Q4 growth initiatives without requiring outside financing. Building a Safe Harbor Floor: Establishing a baseline payment based on 100% or 110% of the prior year's tax liability can provide protection from estimated-tax underpayment penalties when the applicable safe-harbor requirements are satisfied. Aligning Cash Flow: The Annualized Income Installment Method stabilizes cash positions by calculating tax based on income earned during the applicable annualization periods rather than an arbitrary quarterly fraction. Restoring Strategic Headspace: When tax planning is handled reliably behind the scenes, internal finance leaders get their time back to focus on high-level financial modeling instead of chasing K-1s.

Read More >

Contact Information

SF Bay Area Headquarters
111 Anza Boulevard, Suite 320, Burlingame, CA 94010, United States

Phone: (800)837-5160
Email: [email protected]

"Scrubbed" is the brand name under which Scrubbed Advisory, LLC and Scrubbed Assurance, LLP provide professional services. Scrubbed Advisory, LLC and Scrubbed Assurance, LLP practice in an alternative practice structure in accordance with the AICPA Code of Professional Conduct and applicable law, regulations, and professional standards. Scrubbed Assurance, LLP is a licensed independent CPA firm that provides attest services to its clients, and Scrubbed Advisory, LLC provides tax, finance, and support services to its clients. Scrubbed Advisory, LLC is not a licensed CPA firm.

Copyright © Scrubbed. All rights reserved.