Asia Real Estate Forum 2023: Unveiling Opportunities and Insights

Asia Real Estate Forum 2023: Unveiling Opportunities and Insights

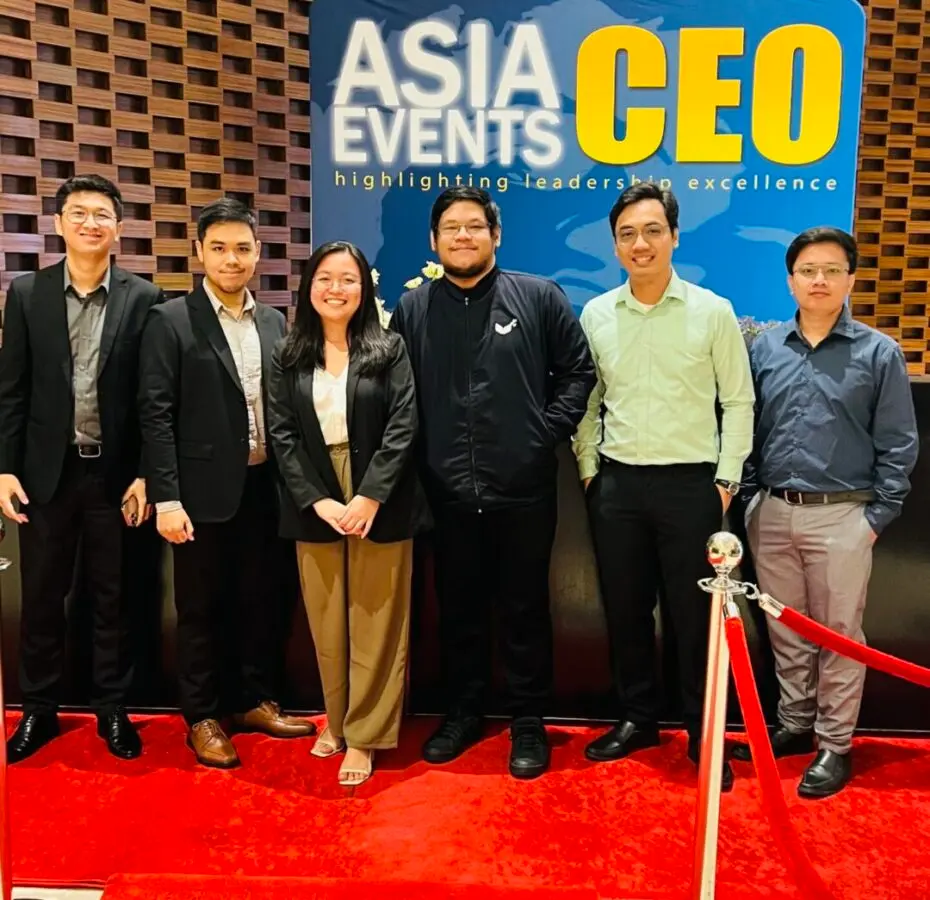
My colleagues MJ, Lem, Chester, Neil, LA, and I were fortunate to attend the 2023 Asia Real Estate Forum on August 24, 2023. The event, themed “Buying Real Estate is Building Dreams on Solid Foundations,” took place at the Manila Marriott Hotel. This proved to be an immensely enriching experience as it provided us with the opportunity to learn from leading industry figures and interact with various stakeholders in the real estate sector.


Looking for Specialized Accounting, Finance, and Tax for Real Estate?  Click here to visit our page now!


The forum boasts an impressive lineup of distinguished speakers, each contributing their expertise to the event. Notable figures include Jen Dela Cruz, Head of Client Services at Figari Group; Jun Palafox, renowned master architect and urban planner at Palafox Associates; Gigi Alcantara, President of PH1 World Developers; Hannah Yulo, CEO of Hotel101 Group; Jaime Bautista, Secretary of the Department of Transportation; Karen Magno, Head of Business and Investment at the Subic Bay Metropolitan Authority; Arlene Reyes, Vice President of Pag-IBIG Fund; Mikko Barranda, Commercial Leasing Director at Leechiu Property Consultants; David Lee, Real Estate Assurance Partner at PWC Singapore; Gisela Kalalo, Executive Vice President of the Bases Conversion Development Authority; and Chad Sotelo, Senior Vice President and Business Unit General Manager at RLC Residences.


Image 20230925 141424 390 scaled qww4tj1r3pjjoxsneby5ag48pe0z87onb150zh3fs8


Here are the significant insights from the forum:


1. The Philippines aims to become a first-world country in the next few decades. Currently, there’s a growing demand for real estate, driven by increasing incomes among Filipinos, similar to the trend observed in neighboring developed nations in the past.


2. The Secretary of the Department of Transportation (DOT) emphasizes the current and forthcoming major transportation projects envisioned by the Philippine government for the next three decades.


3. Efficient, accessible, and reliable transportation is pivotal for real estate growth. Currently, traffic congestion incurs an economic cost of approximately PHP 1.2 trillion.


4. Occupancy remains high due to the prevailing work-from-home trend, but there is a steady increase in demand for office spaces in the Philippines as employees seek more opportunities for work collaboration.


5. As major investors search for new opportunities in Asia, the Philippines is actively competing to seize these prospects. Numerous presentations are highlighting ongoing projects, including new hotels, housing developments, sports centers, and more.


In conclusion, our participation in the 2023 Asia Real Estate Forum was genuinely enlightening and transformative. The forum showcased the nation’s potential as a burgeoning hub for real estate development.


We are grateful for the knowledge and connections gained during this forum, and we look forward to leveraging these insights, as well as our corporate finance advisory expertise as we navigate the ever-evolving real estate landscape in the Philippines. The future holds immense promise, and we are excited to be a part of the journey toward realizing the nation’s real estate aspirations.


How Scrubbed can help you?

The accounting and finance landscape for real estate companies can be challenging. Handling complex lease accounting standards, multiple valuation methods, depreciation and capitalization costs, and tax compliance all need careful attention to detail. Outsourcing with Scrubbed means you’ll have access to up-to-date financial, tax, and forecasting information. Our expertise in delivering tailored real estate accounting solutions ensures you have the financial clarity and insights needed to make strategic investment decisions, manage properties effectively, and develop exit strategies that achieve your goals.


Let’s talk about your real estate business and how Scrubbed can help improve the accuracy of your financial reporting, property management, and investment decisions.

Talk to Our Experts


Looking for a trusted accounting and finance partner for your real estate business? Contact Scrubbed today for a free consultation and discover how our real estate accounting experts can help you improve financial reporting, optimize property performance, and make more informed investment decisions.

CONTACT US
Talk to Our Experts

Related Content

Blogs

7 Numbers Boutique Hotel Owners Should Be Looking At Every Month

7 Numbers Boutique Hotel Owners Should Be Looking At Every Month

Boutique hotel owners don't need to review every line of a monthly financial package to understand how the business is performing. Seven numbers tell most of the story: occupancy, average daily rate (ADR), RevPAR, total revenue, labor costs and productivity, gross operating profit (GOP), and cash. Reviewed together and consistently, they show whether a hotel is pricing rooms well, controlling its largest costs, and generating cash it can actually use. Hotel owners have a lot of numbers coming at them every month. Night audit reports, benchmarking data, P&L statements, labor reports, and bank balances all compete for attention. You don't need to look at everything to know how the business is doing. I've spent more than a decade in hotel finance, from a two-person accounting team at a newly opened boutique hotel to finance leadership roles at Hilton, The Redbury Hotel, and Avalon Hotel Beverly Hills. Across all of them, a handful of numbers, reviewed consistently, told me most of what I needed to know. This matters even more for independent and boutique properties. Many don't have a brand's corporate finance support or a dedicated asset manager, so the owner is often the one who has to notice what changed and ask why. Having co-founded a hospitality company myself, I know how much of that lands on the owner's desk. Here are the seven I think are worth paying attention to. What do occupancy, ADR, and RevPAR tell hotel owners? Occupancy, ADR, and RevPAR measure how well a hotel sells its rooms. Occupancy shows how many rooms you filled. ADR shows what guests paid for them. RevPAR combines the two into one number. Read together, they show whether room revenue is growing through volume, price, or both, and which approach is working. 1. Occupancy Occupancy is the percentage of available rooms sold during a period. It is calculated as rooms sold divided by rooms available. Occupancy drives almost every part of hotel spending. It affects how many housekeepers you schedule, how many operating supplies you use, your utility bills, and even sales in other departments. Every occupied room is also an opportunity to earn more than the room rate, through a dinner reservation, a parking fee, or an event booking. 2. Average Daily Rate (ADR) ADR is the average price guests pay per occupied room. It is calculated as room revenue divided by rooms sold. Higher occupancy is not always better. Every occupied room carries a cost: labor for cleaning, guest amenities, laundry, and utilities. ADR determines how much of each room sale is left after those costs are covered. A stronger rate on the same cost base sends more money to the bottom line. 3. RevPAR Revenue per available room (RevPAR) is calculated as room revenue divided by rooms available, or occupancy multiplied by ADR. It shows the balance between filling rooms and pricing them well. Selling out is not always the goal. Consider a 100-room hotel on a single night: Scenario Occupancy ADR Room Revenue RevPAR Rooms  A  80%  $150  $12,000  $120  80  B  70%  $180  $12,600  $126 70 Scenario B earns more room revenue while servicing 10 fewer rooms. That means lower housekeeping, laundry, and amenity costs on top of the higher revenue. This is why it's worth comparing your RevPAR against your competitive set, typically through benchmarking reports such as STR, rather than chasing a full house. Why should hotel owners look beyond revenue? Total Gross Operating Revenue is only part of a hotel's overall story. While it is important to bring in as much revenue as possible, it is equally important to understand and manage expenses based on forecasted occupancy and income. A property’s operating budget is the initial plan for any given period, but the management team must be ready to adapt when necessary. One of the best metrics to use when budgeting and forecasting is Cost Per Occupied Room (CPOR).  4. Cost Per Occupied Room Cost Per Occupied Room is one of the most effective ways to analyze and forecast expenses in the hotel industry due to its direct relation to usage and consumption by hotel guests. To  achieve ideal profit margins on a monthly basis, variable expenses should be adjusted to maintain the budgeted proportionate spend.  For example, if Guest Amenities are budgeted at a total of $4.50 per occupied room, the finance leader can easily reduce allowed spending $4.50 for every room that falls short to budget. In a month where forecasted occupied rooms are expected to finish below expected occupancy by 300 rooms, the adjusted spend in Guest Amenities for that month can be reduced by $1,350.00 compared to budget. In the opposite scenario, if anticipated occupancy exceeds budget by 300 rooms, the Controller or Director of Finance can hypothetically increase spend by up to $1,350.00 if required to maximize guest experience without sacrificing profit margins.  Which costs have the biggest impact on hotel profitability? Labor is the largest operating expense for most hotels, which makes it the first place to look for profit opportunities. Pairing labor costs with productivity measures, then tracking gross operating profit (GOP), shows whether revenue is actually turning into profit. A busy hotel and a profitable hotel are not always the same thing. 5. Labor Costs and Productivity Track labor in two ways: total cost and productivity. Total cost shows what you spent. Productivity shows whether the hours you scheduled matched the business you actually had. Common productivity measures include housekeeping minutes per occupied room and labor cost per occupied room. Know your target for each, and build schedules from forecasted occupancy rather than last month's schedule. When occupancy dips midweek, hours should follow. When I managed accounting for seven hotels at once, labor productivity reports were part of every monthly package. Seeing properties side by side made it clear how quickly hours drift when schedules aren't tied to the forecast. 6. Gross Operating Profit (GOP) GOP is total revenue minus departmental expenses and undistributed operating expenses, such as administrative and general, sales and marketing, maintenance, and utilities. These categories follow the Uniform System of Accounts for the Lodging Industry (USALI), the standard reporting framework used across the hotel industry. Any management company or asset management team will stress the importance of achieving GOP. If the hotel is falling short of its revenue forecast, expenses should be adjusted so the team still reaches its profit margin goal. Tracking GOP margin (GOP as a percentage of total revenue) and GOPPAR (GOP per available room) makes month-to-month comparisons easier. Every month, I prepared a financial critique for ownership that explained the major variances to budget. It's a habit any owner can borrow: if GOP falls short, you should be able to say which lines moved and why. Why is cash different from profit for a hotel? A hotel can show a profit on its income statement and still run short of cash. Payroll, vendor payments, repairs, taxes, and capital improvements all draw on cash, often on a different schedule than revenue comes in. Owners need to know both what is in the bank today and what the coming months will require. 7. Cash Flow Profit on paper is one thing. Having enough cash for payroll, vendors, repairs, taxes, and upcoming improvements is another. A few hotel-specific items deserve attention. Occupancy taxes collected from guests belong to the taxing authority, so that balance isn't yours to spend. Seasonal properties need to set aside cash for slower months while revenue is still strong. Furniture, fixtures, and equipment (FF&E) also wear out on a predictable cycle, which is why many hotels fund a replacement reserve, often around 3% to 5% of total revenue. Early in my career, I produced daily and weekly cash flow forecasts for multiple hotels. Later, I set up the front desk and accounting cash handling process for a new property. Both taught me the same lesson: cash needs its own attention, separate from the P&L. Look ahead, not just at today's balance. A rolling 13-week cash forecast is a simple way to see what's coming before it arrives. How should boutique hotel owners review these numbers each month? Monthly financials don't need to be complicated. Review the same seven numbers at the same time each month, and compare them against budget, the same month last year, and your competitive set. The goal is not to analyze everything. It's to notice when something changes and ask why before it becomes a bigger problem. A simple monthly routine looks like this: Compare each number to budget and to the same month last year. Look for numbers that should move together but don't, such as occupancy rising while labor productivity falls. Flag anything that doesn't look right and ask your finance team or accountant to explain it. For smaller and independent hotels, what matters is having a few numbers you understand, reviewing them consistently, and asking questions when something doesn't look right. Sometimes the most useful conversation with your accountant starts with just a few numbers. The 7 monthly numbers Metric What is measures How to calculate Question to ask each month  Occupancy  Share of available Rooms sold ÷ rooms available Are we filling rooms at the pace we forecasted?  ADR  Average price paid per occupied room Room revenue ÷ rooms sold  Is our rate in line with demand and our competitive set?  RevPAR  Room revenue earned per available room Room revenue ÷ rooms available How do we compare with our competitive set?  Cost Per Occupied Room (CPOR) The average of spend for any rooms related expense based on each occupied room Total expense ÷ Total occupied rooms  How can I adjust my expenses based on current forecasted occupancy?  Labor costs and productivity  Labor spend and how efficiently hours are used Labor cost ÷ occupied rooms; minutes per occupied room Did scheduled hours match actual occupancy?  GOP  Profit from hotel operations before fixed charges Total revenue - departmental and undistributed expenses Is revenue turning into profit at our target margin?  Cash  Money available to run and maintain the hotel  Current balance + expected inflows - expected outflows Can we cover the next 13 weeks of obligations? Key Takeaways Read room metrics together: Occupancy, ADR, and RevPAR each tell part of the story. Together they show whether revenue is growing through volume, price, or both. Full doesn't always mean better: A hotel can earn more room revenue with fewer occupied rooms when its rate is stronger, and spend less to service them. Look at the whole property: Food and beverage, parking, and events can drive meaningful revenue, especially for boutique hotels. Start with labor: As the largest operating expense, labor is where schedule discipline has the most direct effect on GOP. Plan cash ahead: Profit doesn't pay payroll. A forward-looking cash forecast keeps payroll, taxes, and improvements covered.

Read More >
Blogs

Own the Core, Access the Rest: What The Future is Fractional (TFIF) 2026 Revealed About How Finance Teams Are Being Rebuilt
Own the Core, Access the Rest: What The Future is Fractional (TFIF) 2026 Revealed About How Finance Teams Are Being Rebuilt

The Future Is Fractional (TFIF) 2026 was a virtual conference hosted by Scrubbed on September 24, 2026. The program included an opening keynote, three panels, three industry spotlights on real estate, nonprofit and technology, and a closing conversation on building a finance team. Sixteen speakers and seven moderators took part, including CEOs, CFOs, fractional finance leaders, AI practitioners, and tax and insurance specialists. The day’s core idea came from Scrubbed CEO Vince De Leon : “Own what is core. Get access to the rest.” This article draws together the themes that ran across sessions: finance team structure, AI and human accountability, data and process foundations, permanent readiness, and early information and cash. It’s written for CFOs, controllers, CEOs and founders deciding how to structure their finance function. For decades, building a finance function followed a simple rule. Need a capability, hire someone. Need more capacity, add headcount. Need deeper expertise, hire a specialist. That rule is under strain. Strong controllers and technical accountants are still hard to find. AI can now do real work inside accounting roles. And demand on finance teams rises and falls with closes, audits, fundraising, acquisitions and downturns, while the payroll behind them stays fixed. Those pressures ran through every conversation at The Future Is Fractional (TFIF) 2026 , a virtual conference hosted on September 24, 2026, by Scrubbed, a professional services firm providing accounting, finance, and tax solutions. The event brought together CEOs, CFOs, fractional finance leaders, AI practitioners, and industry specialists across technology, non-profit, and real estate The speakers came from different seats, and they didn’t always agree. But the same three questions kept surfacing: What should a finance team own? What can it reliably access? And what still requires a person? Key Takeaways: Capability is separating from headcount. Talent scarcity, AI and uneven demand are pushing leaders to ask what they need to own and what they can reliably access, rather than who to hire next. Own what depends on context; access what depends on depth or intensity. Roles built on inside knowledge and relationships tend to stay in-house. Specialized or periodic work is a common candidate for fractional or outside support. AI changes the work, not the accountability. Speakers described real gains in coding, extraction, reconciliation review and drafting, and agreed that a named person must review and own the output. Foundations come first. Documented processes and clean, connected data decide how much AI can deliver. Readiness and early information build trust. Audit, fundraising and deal readiness is a standing condition, and boards value being told early over being told precisely. The Bigger Shift: Capability is Coming Apart from Headcount In his opening keynote, Scrubbed CEO Vince De Leon named three forces arriving at once: talent is scarce, AI is here, and demand is becoming more variable. None is new on its own. Together, they weaken the assumption that capability and employment have to be the same thing. His suggested reframe: instead of starting with “Who do we need to hire?”, start with “What capability do we need, and what do we have access to?” Some capabilities belong inside the company. Some are needed only periodically. Others can come from specialists, global teams, fractional leaders or technology. Fractional finance means accessing finance capability, such as a CFO, controller, or specialized accounting expertise, part time or for a specific need instead of through a full time hire. At TFIF 2026, it was framed as separating capability from headcount: owning what is core and accessing the rest. He was careful about what that doesn’t mean. “A bad fractional hire is still a bad hire. A good full-time hire is still valuable.” The standard for judgment, ownership and accountability doesn’t change with the employment model. He left the audience with three questions that the rest of the day kept answering in practice: What capability do I really need to own? What work should no longer require a person? Where am I carrying fixed capacity against variable demand? Finance Team Structure: What to Own and What to Access A hybrid finance team combines in-house staff with outside capability such as fractional leaders, offshore accounting teams, specialists and AI tools. At TFIF 2026, speakers from very different organizations drew the line between the two in similar places. Owned Layer (In-House) Accessed Layer (Fractional, Outsourced or Specialist) What it depends on Inside context, relationships, final accountability Technical depth, periodic intensity, scalable volume Examples raised at TFIF Handling new vendors and unusual charges; grant accounting; reviewing reports; approving AI-assisted work Routine transaction booking; fractional CFO leadership; merger and scaling support; cost segregation, tax credit and insurance expertise Typical role of people Review, interpret, decide Produce, execute, advise The owned layer tends to be about context and relationships. Ottavio Siani , a fractional CFO who also runs an eight-location coffee business, described the split in his own company. His on-site finance person handles anything new, like an unfamiliar vendor or an unusual charge, while an offshore team handles routine booking. The in-house role shifts, in his words, to “You will be reviewing this report. You will not be producing the report.” Costa John , CEO of Chief Assignments, speaking on nonprofit finance, drew the line at the grant accountant, a role built on relationships with program leaders and funders that may not translate if outsourced. He also flagged a common mistake: hiring a fractional CFO for strategic work while the books still don’t close cleanly. The CFO gets pulled back into bookkeeping, which he called “the most expensive way to solve the wrong problem.” The accessed layer tends to be about depth or intensity. Naita Saechao Chialvo , a fractional CFO who works with nonprofits and social enterprises, described keeping a core internal team and flexing in outside expertise for mergers, scaling or strategic initiatives that internal teams, and often budgets, aren’t built for. The real estate panel made the same point about specialists in cost segregation, tax credits and insurance: the experts “fill out your dashboard, and then the owner gets to make decisions.” Stage changes the answer, and speakers read it differently . Thar Casey , CEO of AmberSemi, described a progression from bookkeeper to in-house accountant to fractional CFO once fundraising begins, with in-house leadership eventually needed because investors want institutional knowledge that stays. Others were less sure the flexible layer has to shrink. Marcus Guerro , President of Guerro Enterprises, described an interim placement scoped for two or three months that was still in place five years later. Siani said he had yet to see, at the small and mid-sized companies he works with, a hybrid model that outgrows its third-party resource. The two tend to grow together. Eric Valle , Director of Partnerships at Aduro Advisors, described a lean version of that model: “You don’t need to build an entire finance team, you kind of just need one controller and have that person manage out a team.” The shared conclusion wasn’t that one model wins. It was that team structure is now a decision made capability by capability, rather than a default. The Flexible Layer Only Works When it’s Integrated Access doesn’t come free. Guerro distinguished relationship-based partners from transactional staffing, and firms whose consultants are trained employees with managers behind them from individual contractors working alone. Siani asks prospective accounting partners how many clients each accountant carries (four or five is a good answer; 20 is a warning sign) and whether the team knows his industry. He sets communication rules early and spends the first months showing in-house staff that outside support is there to lighten an overloaded plate, not to replace them. AI in Finance is Changing the Work, and Accountability stays with a Person No session framed AI as a story about eliminating roles. The consistent message was that AI is changing what those roles consist of. The gains described were specific. Dawn Hatch , founding partner and CEO of MATAX, an AI-native accounting firm, pointed to transaction coding at volume, document extraction, first-pass reconciliation review and narrative drafting that gets “about 90% of the way there.” Her less obvious point: AI lets a team review 100% of transactions instead of a sample, so quality improves along with speed. Siani said that across a nine-month engagement rebuilding a client’s finance function, he “didn’t type a single formula into Excel.” He structured and quality-checked the models Claude built instead. The same speakers were blunt about limits. Blaze O’Byrne , co-Founder of Byron, whose company builds AI agents for CPA tax workflows, said the work “shouldn’t be fully handed off to AI today.” Hatch put it more directly: “the reviewer has to own the output, regardless of what is creating the draft.” Siani, who has been hired to clean up after clients adopted tools promising fully automated accounting, advised skepticism toward any such promise. Rusty Canada , co-founder of Ternpoint Solutions, said it “should scare companies” to picture an agent acting in the accounting system without oversight. Session moderator Kendrick Kho , Scrubbed’s Chief AI Officer, added that products branded as an “AI accountant” or “AI chief of staff” can quietly write the human review step out of the process. This connects to a principle De Leon carried from his years as a CTO: “Technology should remove the work. It should not remove the value.” If AI saves three hours and those hours fill with more of the same work, productivity rises. If they go toward understanding the business or making better decisions, the role itself changes. Kho described that shift in accounts payable, where people move from document capture toward vendor work and analysis. AI in Finance is Changing the Work, and Accountability stays with a Person Banning AI tools doesn’t stop their use, Canada noted; it pushes staff toward personal accounts. Kho shared anecdotes of mid-market companies without a ChatGPT business plan discovering 80–90% organic adoption anyway. The practices speakers recommended instead: Practice What It Means Raised By Classify the data, not the tool Tier data as public or anonymized, client-identifying and regulated, so people know what can go where  Hatch Keep an approved tools list with a fast path Vet training terms, retention and sub-processors quickly; slow approvals push people around the rules  Hatch Provide enterprise tools Give staff an enterprise AI account with limited access rather than leaving them to personal ones Canada, O'Byrne Surface Exceptions Route uncertain or unusual items to a person’s attention instead of asking them to recheck everything O'Byrne Name the approver Put a named person on every sign-off, with an audit trail O'Byrne, Hatch Check with a second model Use a separate AI to look for errors in the first one’s output O'Byrne  Run Evaluations Test workflows against known cases, and retest after any model or prompt change Hatch  Go deeper on where AI is delivering measurable ROI in accounting today . The Foundation Comes Before the AI If one idea ran through every AI discussion, it was that AI amplifies whatever it sits on. Hatch said pilots succeed when a documented process exists before the AI arrives and stall when it doesn’t. Otherwise, “you’re just making confusion faster.” Asked how she would spend a hypothetical $500,000 technology budget, she said AI would come last, after core systems, data hygiene and senior reviewers. Skipping those steps, she said, is “buying the faster way to wrong.” Not everyone ordered it that way. O’Byrne’s first move would be to put an enterprise version of ChatGPT or Claude in staff hands, then invest in cybersecurity. Canada would start with the systems stack and outside guidance. The disagreement was about sequence, not about whether the foundation matters. Abdul Wahab Zafar , SVP of Finance at Studycast, made the case from the systems side. Reliable financial data starts upstream: customer, contract and billing data need a common key tying them together. That’s why, in his view, AI makes finance both easier and harder. Reconciliations and reporting get faster, but deeper analysis breaks down when data from different systems doesn’t line up. He also argued that 90–95% data alignment is often more cost-effective than chasing the last 5%. Simplicity was a recurring defense. Zafar urged teams to fully use the systems they already have before buying new ones. Costa John advised growing nonprofits to start with the lightest accounting system that works. Satoshi Steimetz , CFO of Playworks, supplied the counterweight: across 16 regions and 12 departments, a spreadsheet budget is no longer possible. The right system depends on scale. Readiness is a Permanent Operating State Several sessions arrived at the same view of readiness for audits, fundraising, acquisitions and shocks: it’s a standing condition, not a project that starts when a deal appears. Casey described fielding three inbound acquisition inquiries while raising money and knowing his company wasn’t clean enough to respond. His advice: “readiness, readiness, readiness, be ready, always be ready.” Guerro framed the cost. Companies that save a few thousand dollars a year by under-investing in finance can lose millions in valuation when the books aren’t ready for diligence. Asked when a company should start preparing its back office for a possible acquisition, Zafar answered, “as of yesterday.” The real estate panel added a planning version. Blake Peters, founder of Peters Specialty Tax Services, said incentives such as R&D credits and energy efficiency deductions are often “looked at a little too late in the process,” once a project is well underway. Geraldine Serrano, Director of Specialty Tax Group, LLC described an owner-builder who missed tax benefits because the cost segregation conversation happened after construction decisions were made. Alex Gilmete, a commercial property and casualty advisor at USI Insurance Services, warned that a $10 million building could now cost $14 million to $15 million to replace, leaving policies written to old values short. Readiness, in these conversations, wasn’t about perfection. It was about not being surprised by questions that were always going to be asked. Read what mid-market leaders learned redesigning their finance function. Finance earns Trust by Being Early The planning and industry sessions shared a view of what makes finance valuable to leadership. It isn’t precision. It’s timing. Steimetz described a budget miss at Playworks that surfaced in the final quarter of the fiscal year, too late to respond. “The size of the miss mattered less than how late it surfaced.” The organization now reviews revenue weekly, refreshes the full forecast monthly and updates a five-year projection quarterly. His conclusion about boards: “Confidence is not built on being right, it’s built on being early with the information.” Cash was the common measure. Playworks holds enough cash for six months of operating expenses, which Steimetz said lets it absorb bad news and act on opportunities. Costa John suggested every nonprofit board packet show one number: how many days of cash expenses unrestricted, uncommitted reserves can cover. Zafar holds customer payment terms firm while negotiating longer vendor terms, keeping a cushion between cash in and cash out. Information also has to lead somewhere. Danielle Morris, a succession and governance strategist, argued that finance teams need predictive indicators because financial statements are lagging ones. Costa John said boards should get the forward look, its impact, and a range of choices, not a single option to approve or reject. This loops back to structure. A team consumed by closing the books has little time for forward-looking work, which is one reason speakers kept separating compliance capacity from strategic capacity. Explore how finance leaders plan when uncertainty is the baseline. A Diagnostic For Finance Leaders: 8 questions TFIF didn’t produce a universal answer, and its speakers would be the first to say it shouldn’t. Scrubbed CFO Aira Pineda offered a better starting point as she closed Session 1: “You don’t have to build the whole engine yourselves, you just have to know it well enough to know when something’s off, and who to call when it is.” Knowing your function that well starts with a few questions to work through with your team: Where is our finance team stretched? By volume, complexity or timing? Each points to a different fix. Which capabilities depend on the context only an insider has? Those are strong candidates to own. Where are we carrying fixed capacity for variable demand? Think technical accounting during an audit, FP&A during planning, or CFO-level work during a raise. Is our process documented well enough to automate? If not, that’s the first project, before any AI tool.   Who signs off on AI-assisted work, and do they know what they’re checking?   If an acquirer or auditor called tomorrow, would we trust our own data? How early does our board hear about a change in assumptions? If we bring in outside support, how will it work with our team, and who owns that relationship? The Org Chart is Becoming a Design Decision The last generation of finance teams was built by accumulation: a new need, a new hire. TFIF 2026 suggested the next will be built by design. Leaders will decide which capabilities to own, which to access, which work technology should take on, and where a person’s judgment has to stay. That’s harder than hiring by default. It takes knowing your processes well enough to redesign them, your data well enough to trust it, and your business well enough to tell what’s core from what isn’t. The speakers who had done that work described finance functions that held up better under pressure and gave leadership answers sooner. For most finance leaders, the question is no longer whether this shift is coming. It’s which part of their own function to rethink first. Explore the TFIF 2026 conversations Want to go deeper? Each session has its own article: How We Actually Built It (Session 1) : Mid-market leaders on the signs a finance function has outgrown its structure, vetting partners, and the first 90 days of a redesign. AI in the Finance Function (Session 2) : Where AI delivers ROI today, why pilots stall, and a practical governance model for finance teams. Planning Through Permanent Uncertainty (Session 3): Rolling forecasts, scenario planning, cash reserves and keeping board confidence when assumptions shift. Real Estate Spotlight (Session 4): Cost segregation, R&D credits and insurance strategy for multi-property portfolios. Nonprofit Spotlight (Session 4): Liquidity, restricted funds, board reporting and building finance capacity on a tight budget. Technology Spotlight (Session 4): Data integrity, usage-based revenue forecasting, cash flow discipline and M&A readiness. Building Your Finance Team (Session 5): Choosing between in-house and third-party support, vetting a partner, and scaling a hybrid model. Who Spoke at TFIF 2026 Session Moderator Speakers  Keynote: The Future Is Fractional   Vince De Leon, CEO, Scrubbed  Session 1: How We Actually Built It Aira Pineda, CFO, Scrubbed Thar Casey, CEO, AmberSemi; Eric Valle, Director of Partnerships, Aduro Advisors; Marcus Guerro, President, Guerro Enterprises Session 2: AI in the Finance Function  Kendrick Kho, Chief AI Officer Rusty Canada, Partner and Co-founder, Ternpoint Solutions; Dawn Hatch, Founding Partner and CEO, Matax; Blaze O’Byrne, Co-founder, Byron  Session 3: Planning Through Permanent Uncertainty Darwin Pangilinan, Chief Client Officer, Scrubbed  Satoshi Steimetz, CFO, Playworks; Naita Saechao Chialvo, Fractional CFOO and Consultant; Danielle Morris, Founder and Chief Strategist, Triconal   Session 4: Real Estate Spotlight Ejie De Jesus, Partner, Scrubbed Geraldine Serrano, Director, Specialty Tax Group; Alex Gilmete, Commercial Property and Casualty Advisor, USI Insurance Services; Blake Peters, Founder and Principal, Peters Specialty Tax Services Session 4: Nonprofit Spotlight  Laurence Ruelo, Director of Business Development, Scrubbed  Costa John, CAO, CFO Assignments Session 4: Technology Spotlight  Anthony John Rogador, Accounting Advisory Services Manager, Scrubbed Abdul Wahab Zafar, MBA, CMA, SVP of Finance, Studycast Session 5: Building Your Finance Team  Debra Andrews, CMO, Scrubbed Ottavio Siani, Founder, Triangle Coffee, and Fractional CFO The event was hosted by Ruth Angela Dela Cruz and Fran Redoblado.
Read More >
Blogs

September 15 Estimated Tax Deadline: Strategies for Pass-Through Entities

September 15 Estimated Tax Deadline: Strategies for Pass-Through Entities

For growing pass-through entities, the September 15 tax deadline often creates a collision between cash flow and internal capacity. Guessing at estimated payments leaves companies vulnerable to IRS penalties or unnecessarily traps critical working capital meant for Q4 growth. By establishing a Safe Harbor floor and utilizing the Annualized Income Installment Method, companies can align tax outlays directly with actual revenue. When this execution is handled proactively, finance leaders stop playing defense against deadlines and reclaim their time for strategic planning. When a high-growth pass-through entity, such as an S-Corp or a Partnership, comes off an unexpectedly strong summer, revenue is up. This should be a moment for leadership to celebrate and plan their Q4 investments. Instead, the internal finance team often finds themselves staring down a cash crunch they didn't anticipate. The pressure point is September 15. For growing operations, this date is often a collision course. It is not only the deadline for Q3 estimated tax payments, but it is also the extended filing deadline for Forms 1065 and 1120-S . When you have an internal team trying to finalize the previous year's historical data while simultaneously projecting the current year's performance, the structure usually begins to strain. This isn't about a team dropping the ball. It's simply what happens when internal workflows haven't scaled up to match a company's growth. When two major deadlines collide, and the volume is too high, a stretched team has no choice but to improvise. The Cost of "Guesstimating" In a pass-through entity, the business itself generally does not pay federal income tax. Because income from partnerships and S corporations generally passes through to their owners, owners may need to make individual estimated tax payments based in part on their share of the entity’s taxable income When internal teams don't have a dedicated workflow for this, they often get bogged down trying to predict exact year-end profits during a busy quarter. Without a clear mechanism to manage this, I frequently see companies do one of two things: they either underpay and leave themselves vulnerable to IRS penalties, or they overpay to "be safe." Overpaying might feel like the responsible choice in the moment, but it unnecessarily ties up working capital. When these distributions are sized off gross revenue rather than a projection that accounts for deductions or state-level elections, the company pulls more cash out of the operating account than the owners actually owe. That excess traps liquidity that could have been used to fund critical Q4 growth initiatives—like a marketing push or inventory expansion—without seeking outside financing. Establishing an Estimated-Tax Safe Harbor  When our tax professionals step in to manage this process, the very first thing we do is establish a predictable foundation. We immediately build a "Tax Compliance Calendar" integrated with a "Safe Harbor Floor." A useful starting point is determining which estimated-tax safe harbor applies. For many taxpayers, one option is to base required annual payments on 100% of the prior year's tax, increasing to 110% for certain higher-income taxpayers. The current-year 90% test may also apply. Meeting the applicable requirements through timely payments can generally reduce exposure to estimated-tax underpayment penalties. Once that floor is established, we can adjust for the reality of the current year. Aligning Outlays with Actual Cash Flow If a company sees a massive spike in revenue during Q3, the standard installment method might demand a payment that creates a sudden cash flow imbalance. Good intentions won't balance the cash flow at this stage; you need a precise mathematical approach. To stabilize cash flow during a sudden revenue surge, one strategy to consider is the Annualized Income Installment Method . Instead of assuming income is earned evenly throughout the year, the Annualized Income Installment Method determines the owner's required installments based more closely on income earned during the applicable annualization periods State-level PTE tax elections may also provide federal tax benefits by allowing qualifying state income taxes to be paid and deducted at the entity level rather than being subject to the individual SALT deduction limitation. The result? Depending on the state's PTE tax regime, entity-level payments may reduce the state estimated-tax payments otherwise required from individual owners. A deductible PTE tax payment may also reduce the taxable income passed through to owners for federal purposes, which can affect their projected federal estimated-tax liability. Restoring Strategic Headspace When tax planning is handled consistently throughout the year, it changes how a leadership team operates. It can significantly reduce the risk of an "April Surprise." When Q3 estimates are calculated accurately and tied to a deliberate strategy, leadership knows exactly how much capital is truly theirs to spend. Tax shifts from a looming, unpredictable liability into a manageable line item. Just as importantly, the internal finance leader gets their time back. Instead of spending the first two weeks of September finalizing and issuing K-1s, calculating thresholds, and worrying about penalties, they can focus on high-level financial modeling and operational efficiency. A strong tax partner doesn't just run the numbers; they take the friction out of the process so your team can focus forward. When an experienced team handles the heavy lifting behind the scenes, you stop playing defense against IRS deadlines and start using tax strategy as a genuine tool to fund your growth. See how our tax professionals support growing operations and keep execution predictable. Let's talk through how we can support your finance function. Comparing Q3 Tax Strategies: Safe Harbor vs. Annualized Method vs. PTE Strategy Ideal for Primary Benefit Risk Level  100%/110% Safe Harbor  Rapidly growing companies  Provides protection from estimated-tax underpayment penalties when applicable safe-harbor requirements are satisfied  Low (May temporarily tie up cash if revenue drops)  Annualized Method  Seasonal or late-year spiking revenue Align tax outlays directly with timing of taxable income  Moderate (Requires meticulous record-keeping) PTE Tax Election Entities in high-tax states May provide an entity-level federal deduction for qualifying state income taxes while providing state tax benefits to eligible owners Low (Requires state-specific eligibility and election compliance) Key Takeaways: The Deadline Collision: The simultaneous timing of Q3 estimates and extended historical filings places severe strain on internal finance teams when workflows haven't scaled. The Cost of "Guesstimating": Overpaying estimated taxes based on gross revenue ties up liquidity that could otherwise fund critical Q4 growth initiatives without requiring outside financing. Building a Safe Harbor Floor: Establishing a baseline payment based on 100% or 110% of the prior year's tax liability can provide protection from estimated-tax underpayment penalties when the applicable safe-harbor requirements are satisfied. Aligning Cash Flow: The Annualized Income Installment Method stabilizes cash positions by calculating tax based on income earned during the applicable annualization periods rather than an arbitrary quarterly fraction. Restoring Strategic Headspace: When tax planning is handled reliably behind the scenes, internal finance leaders get their time back to focus on high-level financial modeling instead of chasing K-1s.

Read More >

Contact Information

SF Bay Area Headquarters
111 Anza Boulevard, Suite 320, Burlingame, CA 94010, United States

Phone: (800)837-5160
Email: [email protected]

"Scrubbed" is the brand name under which Scrubbed Advisory, LLC and Scrubbed Assurance, LLP provide professional services. Scrubbed Advisory, LLC and Scrubbed Assurance, LLP practice in an alternative practice structure in accordance with the AICPA Code of Professional Conduct and applicable law, regulations, and professional standards. Scrubbed Assurance, LLP is a licensed independent CPA firm that provides attest services to its clients, and Scrubbed Advisory, LLC provides tax, finance, and support services to its clients. Scrubbed Advisory, LLC is not a licensed CPA firm.

Copyright © Scrubbed. All rights reserved.