Overcoming the Evolving Complexities of Going Public through SPACs

Z

Supervisor, Technical Accounting Group

Overcoming the Evolving Complexities of Going Public through SPACs
A Special Purpose Acquisition Company (SPAC) is a non-complex publicly-traded company that aims to acquire a private company. Fueled by a sudden upsurge in these transactions in 2020, SPACs have become very popular and extensively leveraged by private companies and investors. 

But as with all security offerings, the private entity, investors, and even the SPAC itself all face risks when listing a company through a SPAC. By understanding the challenges and risks of taking your business public through a SPAC, you can make the most informed decision about how to proceed.

Looking for Technical Accounting Experts to help with your SPACS? Click here to visit our page.

How a SPAC Works

The purpose of a SPAC is to acquire a company by effecting a merger, or combination, with the potential to de-risk and shorten the initial public offering (IPO) process. If there is no successful acquisition by the end of its life, the SPAC is liquidated and the proceeds from its IPO returned to the shareholders. On the other hand, if the SPAC identifies a target company successfully, there is a mandatory shareholder vote or tender offer process to close the acquisition, commonly referred to as the de-SPAC transaction.
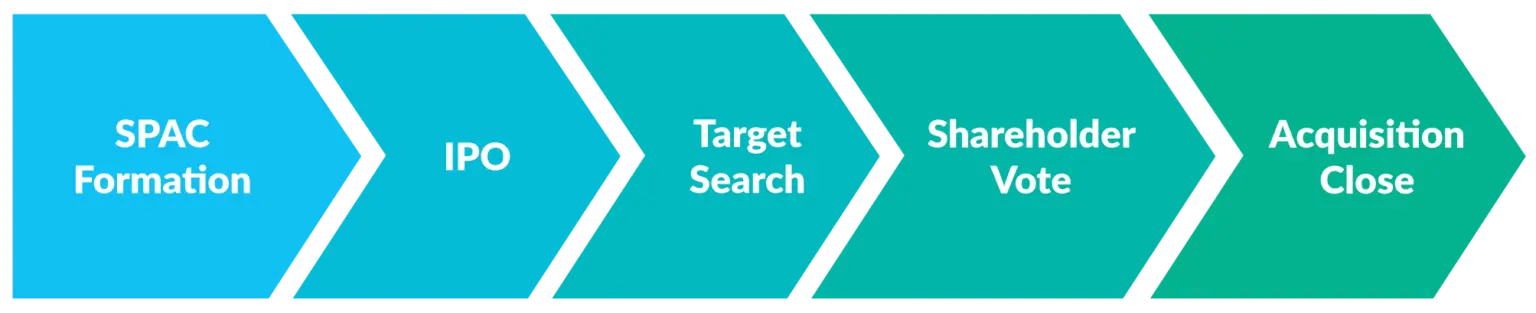
SPAC Lifecycle 02 1536x313


Structure and lifecycle of a SPAC

The SPAC market faces significant challenges on both the regulatory and marketing fronts, including pressure to complete a merger quickly while complying with US Securities and Exchange Commission (SEC) requirements. The SEC recently heightened its scrutiny over SPACs by proposing new rules to enhance investor protection, with additional disclosure requirements for SPACs and their target companies. These new rules aim to eliminate asymmetric information and involve a high level of enforcement activity to safeguard against misleading information and fraud through continuing SEC comments on SPAC filings.

SPAC Mergers vs Traditional IPOs: Benefits and Challenges

SPACs have gained traction in part because they offer several advantages over traditional IPOs.
  • A SPAC is significantly faster to consummate, requiring only three to six months on average vs 12-18 months for a traditional IPO. 
  • A SPAC’s financial sponsors are experienced financial professionals who typically have worked in the industry longer than those who started through regular operating companies. 
  • A SPAC’s financial statements are shorter than an existing operating business that would undergo a traditional IPO, resulting in minimal SEC comments.
  • A SPAC’s price negotiation is done before the transaction closes (whereas a traditional IPO price depends on market conditions at the time it’s listed), and that provides a major advantage in a volatile market.


Despite these advantages, going public through a SPAC merger still presents several challenges and risks.
  • Difficulty finding a target: Searching for a target private company requires extensive due diligence, which could increase the competition among SPACs for high-quality targets.
  • Lack of underwriting and comfort letter: Since a SPAC is already public, it has already prepared the required filings through its underwriter. But a SPAC’s target company may have to go through the process of preparing for these required filings, similar to the process of a traditional IPO.
  • Lack of cash availability from potential redemption: A SPAC’S investors maintain the right to redeem their shares prior to the merger at a pre-defined pro rata price per share. If many more shareholders choose to redeem their shares than the SPAC expected and there is insufficient cash to cover those redemptions, the SPAC may be forced to raise private investment in public entity (PIPE) financing to fill the deficit.
  • Changes and restatements: In 2021 the SEC released accounting reporting updates requiring SPACs to restate their financial statements, including provisions on accounting for warrants and Class A shares presentation and measurement following US GAAP. These changes will require SPACs to work with their technical accountants and auditors to navigate the best path toward a more appropriate accounting treatment and compliant financial statements.
  • Rush deal and merger: A SPAC’s short lifespan (typically about two years) creates pressure to close a deal with a target to avoid liquidation, and that pressure can lead to insufficient due diligence. Investors may look at excessively positive financial projections, resulting in unprecedented investment loss. Getting proper support on due diligence and financial projection analysis is paramount.
  • Compressed timeline for public company readiness: Although the initial formation and merger may be a relief, the target company needs to ready its business to operate as a public company in a short period. If the target doesn’t have strong operating financial controls, it may not be feasible to set them up quickly, given the focused effort it takes to ensure reporting accuracy and meet SEC requirements.
  • Increased timeline and cost: The additional scrutiny and proposed new rules by the SEC are now making the process of going public through a SPAC merger more lengthy and costly.


Best Practices for SPACs and Target Private Entities

A best practices approach can help merger participants overcome these risks and challenges and execute a smooth and faithful deal. The following recommendations provide a good starting point.

Balance sponsor and investor interests 
A successful deal must balance every stakeholder’s interests, including sponsors and investors. Sponsors expect returns in line with the risks they are taking and the expertise they bring, and their payments might be made through conditional share issuances. Independent valuation and merger experts can help protect investors’ interests and ensure due diligence is done appropriately and comprehensively per SEC requirements, while also supporting efforts related to risk and SOX compliance.

Develop complete and accurate disclosures
The SEC has pending guidance on disclosures that favor investors and financial institutions. SPACs should make faithful disclosures on all merger information, including disclosure of potential conflicts, the composition of its sponsors, and the expected cost from IPO until the completion of the de-SPAC transaction.

Prepare the target for de-SPAC requirements   
Going public through a SPAC merger can provide better investment or financing opportunities for the SPAC and the target. However, the de-SPAC entity must have the proper controls in place from the entity level down to the transactional level, all operating effectively and meeting high standards. Engaging in diligent planning and involving experienced accounting and legal experts will ensure that all key processes, including financial reporting, are done according to the highest standards.

What it Means for Accounting and Financial Reporting

Even when a SPAC transaction can overcome these risks and challenges, a de-SPAC transaction will create accounting and financial reporting complexities. The following considerations should be top of mind for all parties involved.
  • Know whether the SPAC is considered a business. As a shell company, a SPAC has no formal business operations and usually only has a sum of cash in its financials. Use caution in assessing whether the SPAC meets the definition provided by the accounting standards and the SEC.  
  • Identify the acquirer and acquiree. Usually this is straightforward, as the acquirer is the one transferring cash/other assets or issuing equity interests. However, the accounting acquirer and acquiree might differ from the legal acquirer and acquiree in certain cases, such as in a reverse acquisition or a reverse recapitalization.
  • Know the applicable accounting standards and disclosures. Usually, the adoption timeline for new standards differs between public and private companies, with public companies adopting new standards a year or more in advance. The private company must be ready to assess the impact and adopt these required standards within the transition period of becoming a listed company.
  • Be prepared to provide documentation requirements. Between the SPAC’s formation to the due diligence phase, and the SEC reporting requirements upon de-SPAC, a handful of documentation is required. This includes but is not limited to: 
  • Super 8-K and Form S-4 or proxy statement with figures and the prospectus
  • Management’s discussion and analysis of the target company and the SPAC
  • Pro forma financial information that includes the expected impact of SPAC transactions
  • Registration statements that are due after the merger
  • Target company’s annual audited financial statements and unaudited interim financial statements reviewed by auditors
  • Other historical financial information of both parties
The target company should also be prepared to consolidate all the public company requirements related to internal control over financial reporting.

The Outlook for SPACs

The de-SPAC process is taking longer and is more onerous than ever, while the combination of additional SEC reporting requirements, rising interest rates, and increased market volatility have caused a recent decline in SPAC activity. However, that doesn’t mean the end for SPACs. 
The SPAC market is evolving and may overcome these challenges in several ways. SPACs might find ways to work around new requirements to provide clarity to their stakeholders. The continued growth in private companies will bring new targets for SPACs to court, potentially creating the next wave of growth. In fact, SPACs seeking new targets have set their sights on several priority industries, including media, telecommunications, healthcare, and life sciences (based on SEC filing analytics). 

How Can Scrubbed Help?     

A SPAC and private company merger can offer significant growth opportunities, but it involves complex steps that require the expertise of accounting and finance professionals who understand the associated requirements. The Scrubbed Technical accounting Group has extensive experience helping companies participating in a SPAC merger achieve the best outcomes. 

We assess IPO readiness, provide technical consultation on complicated accounting transactions involving SPACs, prepare accounting memos, provide audit support, prepare SEC forms reports including 10-Q/10-K, and help address SEC comment letters. Post-IPO, our team can help ease the burden and complexities of ongoing reporting requirements. 

Are you planning to grow your business through a de-SPAC transaction? Contact Scrubbed to learn how we can efficiently and effectively assist you with your goals. Our outsourced accounting professionals and corporate finance advisory team are here to guide you through every step of the process.
Related Content

Blogs

Decoding the Digital Ledger: Navigating FASB’s New Standards for Crypto Assets and Intangibles (ASU 2023-08)

Decoding the Digital Ledger: Navigating FASB’s New Standards for Crypto Assets and Intangibles (ASU 2023-08)

In a groundbreaking move reflecting the swift evolution of the financial landscape, the Financial Accounting Standards Board (FASB) has taken a significant step with the release of the final Accounting Standards Update (ASU) 2023-08 titled “Accounting for and Disclosure of Crypto Assets.” This authoritative guidance specifically addresses Crypto Assets within the Intangibles—Goodwill and Other category, marking a crucial advance in establishing standardized accounting practices for these assets. Bridging the Gap: A Brief Background The rise of digital assets, from cryptocurrencies like Bitcoin and Ethereum to unique non-fungible tokens (NFTs), has challenged traditional accounting norms. Without specific Generally Accepted Accounting Principles (GAAP) guidance, accounting professionals relied on analogies and interpretations, resulting in a diverse patchwork of practices.  Our article “Rise of Digital Assets in Business” explored the evolving landscape, highlighting the AICPA Practice Aid titled “Accounting for and Auditing of Digital Assets” as a crucial guide within the constraints of the existing accounting framework. We are witnessing a groundbreaking shift with the finalized FASB’s ASU on Crypto Assets, effective December 15, 2024, which will change how the world sees crypto assets. Who Will Be Affected? The new ASU applies to a wider range of entities than you might think. Any entity holding crypto assets that meet specific criteria will be impacted. These criteria include: Meet the definition of an intangible asset. Do not grant enforceable rights or claims on underlying goods, services, or assets. Exist on a blockchain-based distributed ledger or similar technology. Are secured using cryptography. Are fungible. Are not created or issued by the reporting entity or its related parties. Crypto assets falling within these criteria must be measured at fair value, with changes in value recognized in their income statement each reporting period. Moreover, transaction costs incurred in acquiring these assets, such as commissions and related fees, will be expensed unless other industry-specific guidance dictates otherwise. A Closer Look at the New ASU  Mandating Relevance: Fair Value Measurement  The update mandates the fair value measurement of crypto assets at each reporting period. This focus on fair value measurement stems from the belief that fair value offers investors more relevant information about the assets’ sale value and changes in that value. The Board rejected historical cost and net realizable value as alternatives due to limitations in reflecting downward and upward price movements. The existing guidance in Topic 820 was deemed sufficient for fair value measurement, given its applicability to other assets and current use by reporting entities. As financial reporting evolves, organizations offering ESG reporting services may also need to consider how such valuation updates intersect with broader transparency and sustainability disclosure requirements. Beyond Annual Assessment: Recognizing Both Gains and Losses Unlike the existing ASC 350 model, which mandates an annual assessment of crypto asset value that only recognizes gains upon sale, the update embraces a more dynamic approach. The new method captures both negative and positive market movements, addressing longstanding concerns about the traditional model’s failure to reflect the true and current economic nature of crypto assets at each reporting period. As well as providing a more comprehensive understanding of the underlying economics and an entity’s financial position, the shift signifies a progressive step toward a more responsive and accurate representation of the financial impact of market fluctuations on digital holdings. Enhancing Transparency: Disclosure Requirements The ASU prioritizes transparency, incorporating detailed disclosure requirements for asset categorization, impairment considerations, and, notably, the separate presentation of crypto assets from other intangible assets in the statement of financial position. Entities must disclose the following for annual and interim reporting periods: 1. Details of significant and less significant crypto asset holdings, including name, cost basis, fair value, and quantity. 2. Information on restricted crypto assets, covering fair value, nature, the remaining duration of restrictions, and circumstances for the potential lapse. For annual reporting periods, additional disclosures are required: 1. A roll forward of crypto asset activity, including additions, dispositions, gains, and losses. Specify the income statement line item for unrecognized gains and losses if not presented separately. 2. Detail dispositions of crypto assets, including sale price, cost basis difference, and relevant activities. 3. The method used to determine the cost basis of crypto assets. These changes enhance transparency and understanding of crypto asset holdings, ensuring comprehensive disclosure for annual and interim reporting periods. Nevertheless, entities immediately converting crypto assets received as noncash consideration or contributions into cash are exempt from the above annual additional disclosures. The Countdown Begins: Timeline and Adoption The final standard takes effect for all entities in reporting periods beginning after December 15, 2024, including interim periods within those fiscal years. Early adoption is permitted, allowing entities to embrace the changes ahead of the mandated timeline. However, early adopters must use a modified retrospective approach, requiring recording a cumulative effect adjustment to equity (or net assets) from the commencement of the adoption year. What Lies Ahead: Implications for the Future The issuance of the finalized ASU 2023-08 represents a proactive response to the growing significance of crypto assets in today’s financial landscape. The finalized ASU is a significant milestone in our journey toward a standardized and transparent future for crypto asset accounting, offering consistency in financial reporting across diverse industries engaged with crypto assets. The FASB’s move acknowledges the need for accounting standards that keep pace with technological advancements and reflect the realities of the modern economy. Stay tuned for further developments. How Scrubbed Can Help You? Navigating the opportunities and challenges of crypto assets demands expertise, whether you’re an individual investor or a business. At Scrubbed, our comprehensive range of services empowers you to stay ahead: • Compliance Experts: Navigate crypto regulations effortlessly with our seasoned professionals. From taxes to reporting, we’ve got your compliance needs covered. • Rock-Solid Controls: Establish secure systems and ensure compliance with the latest financial reporting standards like GAAP and IFRS. • Innovative Strategies: Beyond the numbers, we offer strategic insights about market tren ds and help you make wise decisions. As we collectively pioneer a new era of financial reporting, Scrubbed is committed to bridging the gap between traditional accounting norms and the groundbreaking shifts introduced by the FASB on Crypto Assets. Our Technical Accounting Group is ready to assist your business in decoding the digital ledger, ensuring effective operations, and maintaining compliance with evolving regulations. We also provide specialized biotech accounting services, supporting organizations in highly regulated industries with tailored financial reporting solutions. For a comprehensive consultancy assessment tailored to your specific needs, reach out to [email protected].

Read More >
Blogs

The CPA Firm’s Roadmap to Meeting Tight Audit Deadlines

The CPA Firm’s Roadmap to Meeting Tight Audit Deadlines

Every CPA firm knows the rhythm of the busy audit season: the long hours, the constant pressure, and the impossible balance between speed and accuracy. But what used to be a seasonal challenge has become a deeper structural issue for the profession. With fewer accounting graduates entering the field, growing client demands, and increasing audit complexity, firms can no longer rely on sheer effort to meet deadlines. CPA firm turnover is averaging around 15% nationally and nearly 71% of Big 4 auditors reporting mental health worries due to work pressures . The old model, hire more people, work more hours, simply doesn’t scale. The firms finding success today are the ones rethinking their audit approach. They’re replacing reactive, deadline-driven habits with proactive systems built on planning, visibility, and smart capacity management. This roadmap provides five core, actionable strategies that move beyond wishful thinking and establish a disciplined, collaborative framework to ensure timely completion without sacrificing the integrity of the audit. Step 1: Strategic Planning The planning phase is where you negotiate reality, manage expectations, and build essential time buffers to protect your team. Here’s how this step usually goes: Setting Realistic Timelines The single most destructive action in deadline management is setting a one-sided, unrealistic deadline without client input. This only creates resentment and guarantees delays. Suggested Action: Schedule a dedicated meeting with key client stakeholders early in the process. Use this time to negotiate and agree on an achievable timeline for deliverables, fieldwork, and final sign-off. This collaborative approach manages expectations on both sides and sets a realistic, mutually accepted path forward. When the client agrees to the timeline, they inherently take ownership of meeting their own deliverables, dramatically improving their response time. Buffering for Client Delays Even the most collaborative client will face unexpected internal hiccups. If your internal deadline is the same as the final delivery date, you have no recourse when issues arise. You need built-in protection. Suggested Action: The usual buffer to set is an internal deadline of two days before the official one. This two-day margin serves as your firm’s safety net. Furthermore, when communicating with the client, give them a one or two-day window to provide the necessary information before your internal deadline. This proactive strategy ensures that if the client misses their internal date by a day or two, your firm’s final schedule remains protected, insulating your team from external chaos. Step 2: Focused Execution Once the timeline is set, execution must be focused on ensuring maximum audit efficiency and professional skepticism is applied where it matters most. Prioritizing High-Risk Audits The most efficient audit is not the one that finishes every section fastest but the one that allocates the most senior resources to the areas carrying the highest risk. Suggested Action: Accounts that carry the highest risk of material misstatement must be prioritized and tackled first in peak season. These are the areas that will receive the most extensive and/or detailed audit procedures and require the judgment of senior staff. Common priority areas include: revenue and related accounts (such as Accounts Receivable and Cash), Inventories, Complex accounts (like derivatives or specialized equity), and accounts flagged during planning due to weak internal controls . By front-loading the heavy, high-risk lifting, you surface critical issues early when there is still time to resolve them. Avoiding Bottlenecks Bottlenecks are inevitable, but their impact is manageable. Delays typically stem from a few common issues: a client’s slow response to requests, unexpected material events or errors, and the discovery of mistakes from previous audits. It’s common to encounter one, or even all, of these hurdles during an audit. Suggested Action: When an audit encounters one or more of these hurdles, do not proceed in silence . The moment the delay is quantified, you must immediately renegotiate a new, achievable timeline with the client. Trying to push through an unexpected week-long delay on the original schedule will only lead to rushed, sub-par work. Anticipating and communicating delays early is the hallmark of professional project management. Using Project Trackers While sophisticated audit software exists, the core need remains visibility and accountability for both the firm and the client. Suggested Action: Maintain a simple, centralized project tracker. Often, keeping an Excel file is the most effective low-tech solution. This tracker should monitor the progress of each audit area and, crucially, track what is still needed from the client (the Pending Client List, or PBC). Clear, shared tracking ensures everyone knows the exact status of the engagement and holds the client accountable for their outstanding items. Step 3: Expand Capacity Through Strategic Partnership Even with great planning and process discipline, there’s one reality every CPA firm faces: capacity. This capacity constraint creates the unavoidable bottlenecks that these strategies are designed to mitigate, especially given that the unemployment rate for auditors sits at 2.0%. The talent shortage is the bottleneck. The most effective solution to this crisis is leveraging the dedicated, experienced offshore accounting professionals from Scrubbed. This will allow your firm to instantly scale capacity for high-volume tasks without the overhead or long lead time of permanent hiring, establishing the firm’s forward-looking strategy. Here’s how we make it possible: Audit Support . We handle all your testing, confirmations, and workpaper preparation so your team can focus on analysis and client relationships. Tax Preparation and Compliance. From 1040 and 1120 returns to nonprofit filings, we can help you ensure timely and compliant submissions even during the busy seasons. Accounting and Bookkeeping. We manage your daily bookkeeping, account reconciliations, and month-end close activities, so your team can dedicate more time to strategic initiatives. Transaction and Advisory Support. For firms providing M&A, valuation, or due diligence, we deliver the support you need to strengthen your advisory engagements. As a long-time partner to CPA firms of all sizes, Scrubbed provides access to highly trained accounting and audit professionals who work seamlessly as part of your extended team. We follow your firm’s methodology, align with your tools and standards, and deliver consistent, high-quality work. Beyond Just Meeting the Deadline Meeting tight deadlines shouldn’t come at the expense of your team’s well-being or your firm’s reputation. With the right systems and the right partners in place, it’s possible to deliver every audit on time, with the quality and confidence your clients expect. The ultimate benefit is not just a timely report either, but a sustainable practice. Leveraging proactive steps and strategic partnerships like Scrubbed allows CPA firms to reduce staff stress and burnout, increase the efficiency of review cycles, and consistently deliver high-quality reports, solidifying trust with clients. Don’t let the next busy season dictate your schedule. Partner with Scrubbed to build a resource plan that helps your team meet deadlines without burnout, and deliver quality audits every time.

Read More >
Blogs

The ESG Translation Gap: Why Good Accounting Data Fails Sustainability Audits

The ESG Translation Gap: Why Good Accounting Data Fails Sustainability Audits

If I had to name the first common mistake I see growing companies make when they tackle ESG reporting, it is foundational: They don’t know if the data they are using is complete and accurate. More than that, they often don’t even know if it is the data they should be using. For years, ESG reporting was largely voluntary, a way to answer the public’s demand for accountability and show investors you were responsible. But as optional guidelines transition into emerging laws and requirements, the landscape shifts. Investors and regulators no longer want marketing campaigns. They want accurate data provided with assurance. This brings us to a harsh reality I share with teams newly subject to these regulations: If you are required to file a report in 2027 based on 2026 data, and you wait until 2026 to start preparing, you are already late. Leaders often assume their existing accounting systems are naturally ready to handle ESG reporting. They almost never are. The Illusion of Alignment I see leadership teams fall into this trap constantly. They look at their organizational chart, see a separate Finance team and a separate ESG team, and assume they are covered. But in practice, these two teams are working in silos, speaking entirely different languages. I see this pattern constantly with companies that have been publishing ESG reports voluntarily for a number of years. As they prepare for mandated regulatory reporting, leadership feels secure because their ESG team is getting the exact reports they requested from Finance. But the moment you dig into the architecture and bridge the two teams, the gaps become obvious. Here is how the breakdown usually happens: The Ask: The ESG team needs data to calculate emissions, so they ask Finance for certain reports. The Hand-off: Finance, wanting to be helpful, pulls the data and hands it over. The Gap: Finance teams are wired to be compliant with accounting standards, but they aren’t trained to understand ESG reporting. ESG teams are great at translating finance data into emissions, but they don’t have the concept of an audit. Because the ESG team didn’t have an audit background, they didn’t know how to establish completeness and accuracy. They didn’t know how to look for certain accounting transactions that would otherwise be considered emission or non-emissive (i.e., advance or duplicate payments, reversed entries in the vendor reports). They were running calculations on raw data. The people didn’t fail: the structure simply wasn’t built to translate between the two departments. The Reality of Retroactive Cleanup The true operational complexity of ESG reporting reveals itself when you try to force accounting data into sustainability buckets. Take something as standard as a growing portfolio of leased facilities. From a purely financial perspective, a company might have these perfectly recorded. But you cannot translate that 1:1 to ESG data. For ESG, you have to review the business structure to see who actually holds ‘operational control’ so you can assign those facilities to the proper emissions categories.. When a company’s data architecture isn’t set up for this level of granularity, teams are forced to go back and manually revisit hundreds of outstanding contracts. What should take a minute to encode upfront easily turns into a multi-month project just to find the proper data sources. When you wait to build the system, you force your teams to look backward instead of forward. What You Need to Check Today The fix is actively bridging the technical gap. You need professionals who can translate complex sustainability metrics into an accounting standard, and vice versa. If you are a CFO or sustainability leader reading this today, before making your next public ESG commitment, take a hard look at your architecture. Ask yourself these three questions: Are my on-book activities scoped properly? Check if all financial transactions have been mapped to the appropriate ESG requirement. Are my off-book activities accounted for? Ensure your people management, technology, and operational data are fully captured. Are all stakeholders involved? If ESG reporting is falling entirely on your Finance team, or solely on your ESG team without Finance’s oversight, you have a translation gap. Operations, HR, and Tech must understand the why and the how of the data they are providing. A calm, predictable reporting cycle is designed, never improvised. Build the data architecture a year or two before the regulations hit, and ensure your financial execution naturally supports confident sustainability reporting.

Read More >

Contact Information

SF Bay Area Headquarters
111 Anza Boulevard, Suite 320, Burlingame, CA 94010, United States

Phone: (800)837-5160
Email: [email protected]

"Scrubbed" is the brand name under which Scrubbed Advisory, LLC and Scrubbed Assurance, LLP provide professional services. Scrubbed Advisory, LLC and Scrubbed Assurance, LLP practice in an alternative practice structure in accordance with the AICPA Code of Professional Conduct and applicable law, regulations, and professional standards. Scrubbed Assurance, LLP is a licensed independent CPA firm that provides attest services to its clients, and Scrubbed Advisory, LLC provides tax, finance, and support services to its clients. Scrubbed Advisory, LLC is not a licensed CPA firm.

Copyright © Scrubbed. All rights reserved.