Simplifying the Test for Goodwill Impairment

Marc Santos

Accounting Supervisor

Simplifying the Test for Goodwill Impairment

The complexities of goodwill impairment often present a challenge for companies. During a business combination, the excess of the amount of consideration paid by an acquirer and the net asset’s fair value of the acquiree is known as goodwill. When the value of the net asset of a reporting unit declines, goodwill impairment may have occurred.


Further exacerbated by macroeconomic facts such as inflation, employment levels, national income, and international trade, which affects the valuation and health of both publicly listed and private companies, valuing the fair value of companies presents a challenge, especially the determination if there are impairment of a company’s value.


The current guidance in ASC 350, Intangibles—Goodwill and Other, requires a two-step assessment to determine whether goodwill is impaired.


The first step is to compare each entity’s reporting unit’s carrying value, including goodwill and implied fair value. The second step must be performed if the implied fair value is less than the carrying amount. The second step is to compare the goodwill’s carrying value to its implied fair value and record an impairment charge for any excess carrying value over the implied fair value.


Accounting Standards Update 2017-04 (ASU 2017-04) provides a simpler goodwill impairment test by eliminating the second step to simplify the goodwill impairment test and provide cost savings for all entities.


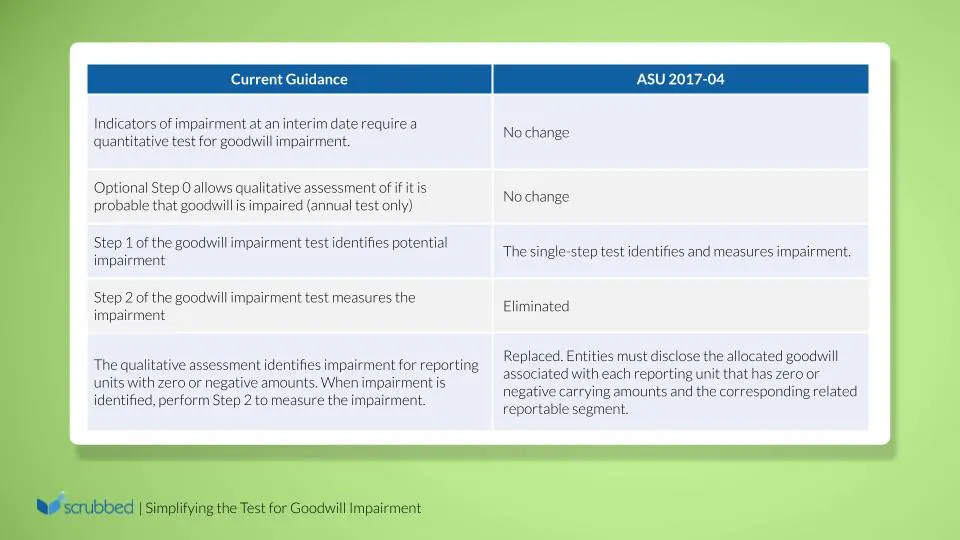
Impact of ASU 2017-04 on Goodwill Impairment Test at a Glance:
Simplifying the Test for Goodwill Impairment 1

Key Discussion

Goodwill is an asset representing the future economic benefits arising from other assets acquired in a business combination that are not individually identified and separately recognized. The goodwill’s unit of accounting is at the reporting unit level. A reporting unit is an operating segment or one level below an operating segment (a component). A component of an operating segment is deemed a reporting unit if it meets the definition of a business in ASC 805, Business Combinations for which discrete financial information is available and whose operating results are regularly reviewed by segment management.


Operating segments or components with similar economic characteristics should be aggregated into one or more reporting units. However, components that are part of different operating segments may not be combined into a single reporting unit. Reportable segments are irrelevant in the determination of reporting units. Goodwill is assigned to specific reporting units for purposes of the annual or interim impairment assessment and, therefore, identification of an entity’s reporting units is the cornerstone of goodwill impairment testing.


Under the current guidance in ASC 350, goodwill impairment exists when the implied fair value of goodwill is less than its carrying amount. Determining the implied fair value of goodwill follows the same approach as calculating goodwill recognized in a business combination. This measurement process is currently referred to as Step 2 of the goodwill impairment test. To perform step 2, an entity must assign a reporting unit’s fair value to all of that unit’s assets and liabilities (including any unrecognized intangible assets) as if the reporting unit had been acquired in a business combination.


The amendment in ASU 2017-04 changes the concept of impairment from a condition that exists when the carrying amount of goodwill exceeds its implied fair value to a condition that exists when the carrying amount of a reporting unit exceeds its fair value. Accordingly, step 2 of the goodwill impairment test is now eliminated. A goodwill impairment loss is measured as the excess of the carrying amount of a reporting unit, including goodwill, over its fair value, which is limited to the allocated total amount of goodwill to that reporting unit. The related income tax effect from any tax-deductible goodwill on the carrying amount of the reporting unit should be considered when measuring the goodwill impairment loss.


Goodwill Impairment Testing Sequence

A: Optional Qualitative Assessment 

ASU 2017-04 did not introduce any changes to the optional qualitative assessment. An entity may choose to perform a qualitative assessment in which qualitative factors such as macroeconomic conditions, industry and market considerations, cost factors, overall financial performance, and other entity-specific events and circumstances are assessed to determine whether it is more likely than not that the fair value of a reporting unit is less than it’s carrying amount, including goodwill. The process of qualitative assessment for any reporting unit in any period may be bypassed. Thus, an entity may perform the quantitative goodwill impairment test directly.


B: Quantitative Goodwill Impairment Test

  1. If the reporting unit’s carrying amount is less than its fair value, then its goodwill is considered not impaired.
  2. If the carrying amount of a reporting unit exceeds its fair value, an impairment loss should be recognized in the amount of the excess and limited to the total amount of goodwill allocated to that reporting unit. Additionally, an entity should consider the income tax effect from any tax-deductible goodwill on the reporting unit’s carrying amount, if applicable, when measuring the goodwill impairment loss.
  3. Once a goodwill impairment loss is recognized, the adjusted carrying amount of goodwill will become its new accounting basis.
  4. Subsequent reversal of a previously recognized goodwill impairment loss is prohibited once the measurement of that loss is recognized.

Tax Deductible Goodwill

In certain jurisdictions, goodwill is deductible for tax purposes for some business combinations. In such jurisdictions, when a business acquisition takes place, a deferred tax asset or deferred tax liability is recorded based on the variance between the tax basis and the book basis of goodwill. Therefore, the impairment of goodwill would create a cycle of impairment when a reporting unit’s goodwill is tax deductible. This is because the decrease in the book value of goodwill will increase the deferred tax asset (or decreases the deferred tax liability). As a result, the reporting unit’s carrying amount will also increase. However, there is no corresponding increase in the reporting unit’s fair value, which could trigger another impairment test since the carrying amount will again be higher than the fair value because of the effect on the deferred tax asset or liability.


To address this issue, the guidance now requires an entity to calculate the impairment charge and the deferred tax effect using a simultaneous equations method comparable to the approach used for measuring goodwill and related deferred tax assets during a business combination. This means that when there is tax-deductible goodwill, further goodwill reduction must be recognized during impairment to offset the increase in deferred tax asset or decrease in deferred tax liability. This will result in the reporting unit’s carrying value equal to its fair value.


Reporting Units with Zero or Negative Carrying Amounts

Before ASU 2017-04, under US GAAP, a qualitative assessment was required to determine whether there was a likelihood of impairment of goodwill associated with having a net asset carrying amount of zero or negative. If the qualitative analysis indicated goodwill impairment, Step 2 would be performed to determine the existence and amount of impairment for that reporting unit.


However, with the implementation of ASU 2017-04, the requirement for conducting a qualitative assessment for reporting units with zero or negative carrying amounts has been eliminated. The same impairment assessment thus applies to all reporting units. In addition, entities that have one or more reporting units with zero or negative carrying amounts of net assets should disclose the reporting units with allocated goodwill, including the amount of goodwill allocated to each and in which reportable segment the reporting unit is included.


Transition Requirements and Effective Date

ASU 2017-04 should be applied prospectively. Public Business Entities that are SEC filers have already adopted the ASU last 2020 reporting. For all other entities, the ASU will be effective beginning the calendar year-end 2023 and thereafter.
How Can Scrubbed Help?


We can assist you by evaluating specific scenarios related depending on your industry related to the changes in ASU 2017-04. In addition, we provide technical consultation on complicated accounting transactions, prepare accounting memos, and provide audit support. Our team can help you ease the burden and complexities of ongoing reporting requirements such as nonprofit financial reporting, risk and SOX compliance, and the application of complex accounting matters.

CONTACT
How Can Scrubbed Help?

Related Content

Blogs

September 15 Estimated Tax Deadline: Strategies for Pass-Through Entities

September 15 Estimated Tax Deadline: Strategies for Pass-Through Entities

For growing pass-through entities, the September 15 tax deadline often creates a collision between cash flow and internal capacity. Guessing at estimated payments leaves companies vulnerable to IRS penalties or unnecessarily traps critical working capital meant for Q4 growth. By establishing a Safe Harbor floor and utilizing the Annualized Income Installment Method, companies can align tax outlays directly with actual revenue. When this execution is handled proactively, finance leaders stop playing defense against deadlines and reclaim their time for strategic planning. When a high-growth pass-through entity, such as an S-Corp or a Partnership, comes off an unexpectedly strong summer, revenue is up. This should be a moment for leadership to celebrate and plan their Q4 investments. Instead, the internal finance team often finds themselves staring down a cash crunch they didn't anticipate. The pressure point is September 15. For growing operations, this date is often a collision course. It is not only the deadline for Q3 estimated tax payments, but it is also the extended filing deadline for Forms 1065 and 1120-S . When you have an internal team trying to finalize the previous year's historical data while simultaneously projecting the current year's performance, the structure usually begins to strain. This isn't about a team dropping the ball. It's simply what happens when internal workflows haven't scaled up to match a company's growth. When two major deadlines collide, and the volume is too high, a stretched team has no choice but to improvise. The Cost of "Guesstimating" In a pass-through entity, the business itself generally does not pay federal income tax. Because income from partnerships and S corporations generally passes through to their owners, owners may need to make individual estimated tax payments based in part on their share of the entity’s taxable income When internal teams don't have a dedicated workflow for this, they often get bogged down trying to predict exact year-end profits during a busy quarter. Without a clear mechanism to manage this, I frequently see companies do one of two things: they either underpay and leave themselves vulnerable to IRS penalties, or they overpay to "be safe." Overpaying might feel like the responsible choice in the moment, but it unnecessarily ties up working capital. When these distributions are sized off gross revenue rather than a projection that accounts for deductions or state-level elections, the company pulls more cash out of the operating account than the owners actually owe. That excess traps liquidity that could have been used to fund critical Q4 growth initiatives—like a marketing push or inventory expansion—without seeking outside financing. Establishing an Estimated-Tax Safe Harbor  When our tax professionals step in to manage this process, the very first thing we do is establish a predictable foundation. We immediately build a "Tax Compliance Calendar" integrated with a "Safe Harbor Floor." A useful starting point is determining which estimated-tax safe harbor applies. For many taxpayers, one option is to base required annual payments on 100% of the prior year's tax, increasing to 110% for certain higher-income taxpayers. The current-year 90% test may also apply. Meeting the applicable requirements through timely payments can generally reduce exposure to estimated-tax underpayment penalties. Once that floor is established, we can adjust for the reality of the current year. Aligning Outlays with Actual Cash Flow If a company sees a massive spike in revenue during Q3, the standard installment method might demand a payment that creates a sudden cash flow imbalance. Good intentions won't balance the cash flow at this stage; you need a precise mathematical approach. To stabilize cash flow during a sudden revenue surge, one strategy to consider is the Annualized Income Installment Method . Instead of assuming income is earned evenly throughout the year, the Annualized Income Installment Method determines the owner's required installments based more closely on income earned during the applicable annualization periods State-level PTE tax elections may also provide federal tax benefits by allowing qualifying state income taxes to be paid and deducted at the entity level rather than being subject to the individual SALT deduction limitation. The result? Depending on the state's PTE tax regime, entity-level payments may reduce the state estimated-tax payments otherwise required from individual owners. A deductible PTE tax payment may also reduce the taxable income passed through to owners for federal purposes, which can affect their projected federal estimated-tax liability. Restoring Strategic Headspace When tax planning is handled consistently throughout the year, it changes how a leadership team operates. It can significantly reduce the risk of an "April Surprise." When Q3 estimates are calculated accurately and tied to a deliberate strategy, leadership knows exactly how much capital is truly theirs to spend. Tax shifts from a looming, unpredictable liability into a manageable line item. Just as importantly, the internal finance leader gets their time back. Instead of spending the first two weeks of September finalizing and issuing K-1s, calculating thresholds, and worrying about penalties, they can focus on high-level financial modeling and operational efficiency. A strong tax partner doesn't just run the numbers; they take the friction out of the process so your team can focus forward. When an experienced team handles the heavy lifting behind the scenes, you stop playing defense against IRS deadlines and start using tax strategy as a genuine tool to fund your growth. See how our tax professionals support growing operations and keep execution predictable. Let's talk through how we can support your finance function. Comparing Q3 Tax Strategies: Safe Harbor vs. Annualized Method vs. PTE Strategy Ideal for Primary Benefit Risk Level  100%/110% Safe Harbor  Rapidly growing companies  Provides protection from estimated-tax underpayment penalties when applicable safe-harbor requirements are satisfied  Low (May temporarily tie up cash if revenue drops)  Annualized Method  Seasonal or late-year spiking revenue Align tax outlays directly with timing of taxable income  Moderate (Requires meticulous record-keeping) PTE Tax Election Entities in high-tax states May provide an entity-level federal deduction for qualifying state income taxes while providing state tax benefits to eligible owners Low (Requires state-specific eligibility and election compliance) Key Takeaways: The Deadline Collision: The simultaneous timing of Q3 estimates and extended historical filings places severe strain on internal finance teams when workflows haven't scaled. The Cost of "Guesstimating": Overpaying estimated taxes based on gross revenue ties up liquidity that could otherwise fund critical Q4 growth initiatives without requiring outside financing. Building a Safe Harbor Floor: Establishing a baseline payment based on 100% or 110% of the prior year's tax liability can provide protection from estimated-tax underpayment penalties when the applicable safe-harbor requirements are satisfied. Aligning Cash Flow: The Annualized Income Installment Method stabilizes cash positions by calculating tax based on income earned during the applicable annualization periods rather than an arbitrary quarterly fraction. Restoring Strategic Headspace: When tax planning is handled reliably behind the scenes, internal finance leaders get their time back to focus on high-level financial modeling instead of chasing K-1s.

Read More >
Blogs

How to Scale a Fractional CFO Practice: Infrastructure, AI, and Execution

How to Scale a Fractional CFO Practice: Infrastructure, AI, and Execution

Fractional CFOs scale by separating strategy from daily execution. At the CFO Leadership Conference in Boston, panelists outlined the model: a three-part team structure, AI tools for repetitive analysis, and strict scope boundaries. The common thread is that strategic capacity depends on reliable accounting operations underneath it. Fractional CFOs operate in a fundamentally different model, balancing multiple clients and shifting priorities without the benefit of deep organizational embedding. You are hired to provide altitude, clarity, and rapid impact. But when a client lacks a mature finance operation, that executive focus is quickly consumed by operational cleanup. This exact tension took center stage at the CFO Leadership Conference in Boston. During our morning panel discussion, The Multi-Business Executive: How Fractional CFOs Scale Leadership Across Clients , moderated by Scrubbed’s Accounting Director Arian David, Triangle Coffee founder and fractional CFO Ottavio Siani and Scrubbed’s CFO Aira Pineda detailed how fractional CFOs build capacity to avoid this operational trap. They mapped out the real-world infrastructure and AI practices required to support multiple fast-moving client environments. Here are the operational realities shared in the room. The Infrastructure Blueprint for Scaling a Fractional CFO Practice A primary challenge for scaling organizations is the gap between strategic desires and foundational accuracy. Volume increases faster than structure, and founders frequently bottleneck their own operations by micromanaging the finance function. As Aira shared with the room, stepping into a fractional role often means untangling founder-led accounting and directly telling the CEO, "you're not supposed to do this". Once leaders step back from the daily execution, "suddenly they have time" to actually focus on growing their business. Successful practitioners build a deliberate team architecture to handle the volume. To build a sustainable infrastructure, Ottavio explained that a fractional CFO setup requires three key elements: A fractional CFO to provide strategic direction. A trusted internal employee to manage sensitive operational context. An external accounting firm to run the daily numbers. This structure prevents the CFO from becoming the operational bottleneck. Read: Are Fractional CFOs the Future for Growing Companies? Navigating Risk in Founder-Led Environments The most pointed friction in a fractional role often comes from enforcing structure. During the session, an audience member challenged the panel on how to balance strict risk controls with the commercial reality of working for independent founders who operate as the "gods of their own businesses". Aira addressed this tension directly, clarifying that operational controls and commercial growth do not have to collide.  "I don't think it's contradictory, to be honest. I think it's complementary," she explained.   "I think you make better decisions as a CFO, having kind of just at the back of your mind that risk mindset." Taking calculated risks is necessary to create shareholder value. However, a fractional CFO can only support that aggressive growth when the foundational accounting operations are secure enough to absorb the complexity. Building Fractional CFO Capacity with AI Tools Technology accelerates this architecture when carefully managed. Ottavio shared how he uses Claude to generate monthly financial statement analyses based on tested templates, reducing a repetitive task to minutes. Arian detailed using Claude to abstract private equity contracts, while Aira highlighted using NotebookLM to summarize 50-page forensic documents. However, systems create results, but human professionals must validate them. Aira illustrated the danger of false confidence by testing a complex revenue recognition issue across Claude, Gemini, and ChatGPT. Although all three models provided the exact same answer, they failed the final human review when  "A big CPA firm comes and says, no, that's not the accounting treatment." Designing Aligned Execution and Preventing Scope Creep Growth adds complexity. Strong execution ensures that complexity remains manageable. When fractional leaders possess a reliable accounting layer, closes become predictable and strategic conversations gain traction. Without this layer, scope creep inevitably takes over. "I think a challenge with being a fractional CFO is having to limit your scope, right?" Ottavio noted. "I typically dedicate like a day a week, and I need to keep myself from spending too much time outside of the original scope that we, we agreed upon, so that I can make sure that I'm kind of meeting all my clients". Key Takeaways: A sustainable fractional CFO practice separates strategy from execution: the CFO, a trusted internal employee, and an external accounting team each hold a distinct role. Founders bottleneck their own operations by staying in the daily accounting. Helping them step back frees time for growth. Risk mindset and commercial growth are complementary. Calculated risks require stable accounting operations underneath them. AI tools like Claude and NotebookLM compress repetitive analysis from weeks to minutes, but experienced professionals must verify every output against source documents. Scope discipline holds only when a reliable accounting layer runs the day-to-day work. About the Panelists Arian David | Accounting Director, Scrubbed  Arian serves as the Accounting Director for Retail and Distribution at Scrubbed. She brings over 12 years of specialized execution experience managing complex accounting operations across the distribution, e-commerce, and retail sectors.  Aira Pineda | CFO, Scrubbed  Aira directs financial strategy and operations as the Chief Financial Officer at Scrubbed. She brings over a decade of hands-on experience operating as a fractional CFO for small to medium-sized enterprises. Ottavio Siani | Fractional CFO & Founder, Triangle Coffee  Ottavio is the founder of Triangle Coffee, a multi-location café business operating in Boston and Washington, D.C. As an active fractional CFO, he advises a portfolio of clients, including Hon, CN Naturals, and Port of Mocha, on building and restructuring finance teams. 

Read More >
Blogs

Scaling Your Finance Function: When to Hire a Fractional Finance Team

Scaling Your Finance Function: When to Hire a Fractional Finance Team

As noted at the CFO Leadership Conference, volume often outpaces structure, quietly straining finance execution. To scale capacity, growing companies can integrate partner-led finance teams anchored by an internal liaison. By taking responsibility for this daily execution, these professionals restore predictable reporting and give leaders their focus back. For many middle-market companies, there is a distinct moment when the finance function shifts from supporting the business to struggling to keep up. Transaction volume increases. Deadlines tighten. The close starts taking longer, and reviews feel rushed. Internal teams spend more time fixing issues than moving forward. During our afternoon panel at the CFO Leadership Conference in Boston, How CFOs Use Fractional Talent to Scale the Finance Function, Triangle Coffee founder and Fractional CFO Ottavio Siani, Scrubbed’s CFO Aira Pineda, and Accounting Director Arian David unpacked a critical reality for growing organizations. Building a finance organization that can flex with the business requires deliberate structural choices. Here is a closer look at how to architect that structure by integrating partner-led finance teams. When to Hire: The 160-Hour Threshold Prompted by Arian to define the trigger point for bringing on fractional help, Scrubbed CFO Aira Pineda highlighted a practical threshold: evaluating whether a role truly demands a full-time, 160-hour-per-month commitment.  This evaluation is a cornerstone strategy for companies navigating new growth stages. Fast-moving projects often require immediate, specialized execution.  " Sometimes I need a project very quickly done, and I need someone experienced already ," Aira explained. " I don't want to go through the headache [of hiring full-time]. A fractional team just makes it faster for me. " Partner-led finance teams offer a cost-effective alternative to full-time hiring, providing the exact capacity needed without the overhead of onboarding. They take responsibility for the work behind your numbers, allowing the internal team to focus on strategic growth. Full-Time vs. Fractional Finance Team Comparison Feature Full-Time Finance Hire Fractional Finance Team Capacity Commitment Onboarding & Ramp Time Billing Model Specialization 160+ hours/month (Fixed) 60–90 days Annual Salary + Benefits + Equity Generalist execution Flexible / Scalable capacity Immediate deployment Flat Monthly Retainer Multi-disciplinary experts  Best Used For  Continuous daily operations  Fast growth, specialized projects, scaling The Architecture of Integration: The "Bridge" Person A fractional finance team cannot work effectively in isolation. Fractional CFO Ottavio Siani, who systematically leverages these exact structures across multiple ventures to scale his own executive leadership,  identified a critical requirement for successful integration: designating an internal "bridge" person. This full-time employee acts as the primary point of contact between the company and the fractional team. They do not need deep accounting expertise. Their value lies in providing internal context and answering day-to-day questions while the company operates.  When communication paths and responsibilities are clearly defined, fractional professionals can operate as an extension of the internal finance function rather than as a disconnected outside vendor. Best Practices for Integrating a Fractional Finance Team A fractional finance function only succeeds when it is treated as an integrated part of the business. The Standard of Accuracy : Accuracy is a non-negotiable requirement. As Aira noted during the panel discussion, "We work with numbers, and accuracy matters. If we end up, as a CFO, presenting a wrong number to our board... that is grounds for termination." Match the Billing Model to the Engagement : While hourly billing is common for initial testing, Ottavio strongly advocated for flat-fee models to maintain strategic alignment. "The problem with hourly billing is the company ends up being pretty precious with your time, and you'll often be held out of important meetings," Ottavio noted. "Retainer-based [billing] leads to a much healthier relationship." Demand Verified Data Controls (SOC 2) : Handing over financial workflows requires absolute trust. Middle market businesses must partner with CPA firms that maintain rigorous, verified controls, such as a SOC 2 audit, to guarantee data security. Scaling with Technology and Distributed Talent A fractional model also allows companies to broaden the talent pool available to the finance function. Distributed teams can provide access to specialized skills, additional coverage, and capacity that adjusts as the business changes. However, location alone does not determine whether the model will work. Quality depends on how the team is managed, how communication is structured, how the work is reviewed, and whether the provider understands the company’s accounting requirements and operating environment. Technology can further expand the team’s capacity. During the panel, Aira described analytics teams using AI-assisted tools to write Python code and process data more efficiently than manual Excel workflows would allow.  The value is not simply that the technology moves faster. It reduces repetitive work, so finance professionals can spend more time reviewing outputs, investigating exceptions, and applying judgment. Technology can accelerate the work. Accountability remains human. Building the Right Finance Structure Fractional support works best when it solves a defined structural need.  The company must still establish internal ownership. Responsibilities must be clear. Workflows must be documented. Review standards must be understood by both teams.  When those elements are in place, a fractional finance team can help the business: Add capacity without immediately adding permanent headcount. Access specialized expertise. Support periods of rapid growth or transition. Make the close and reporting process more predictable. Reduce pressure on internal finance leaders. Create a stronger foundation for future hiring. The objective is not to outsource responsibility. It is to build a finance function with the right capacity, expertise, and structure for the company’s current stage of growth. About the Panelists Arian David | Accounting Director, Scrubbed  Arian serves as the Accounting Director for Retail and Distribution at Scrubbed. She brings over 12 years of specialized execution experience managing complex accounting operations across the distribution, e-commerce, and retail sectors.  Aira Pineda | CFO, Scrubbed  Aira directs financial strategy and operations as the Chief Financial Officer at Scrubbed. She brings over a decade of hands-on experience operating as a fractional CFO for small to medium-sized enterprises. Ottavio Siani | Fractional CFO & Founder, Triangle Coffee  Ottavio is the founder of Triangle Coffee, a multi-location café business operating in Boston and Washington, D.C. As an active fractional CFO, he advises a portfolio of clients, including Hon, CN Naturals, and Port of Mocha, on building and restructuring finance teams. 

Read More >

Contact Information

SF Bay Area Headquarters
111 Anza Boulevard, Suite 320, Burlingame, CA 94010, United States

Phone: (800)837-5160
Email: [email protected]

"Scrubbed" is the brand name under which Scrubbed Advisory, LLC and Scrubbed Assurance, LLP provide professional services. Scrubbed Advisory, LLC and Scrubbed Assurance, LLP practice in an alternative practice structure in accordance with the AICPA Code of Professional Conduct and applicable law, regulations, and professional standards. Scrubbed Assurance, LLP is a licensed independent CPA firm that provides attest services to its clients, and Scrubbed Advisory, LLC provides tax, finance, and support services to its clients. Scrubbed Advisory, LLC is not a licensed CPA firm.

Copyright © Scrubbed. All rights reserved.