Unlocking Green Tax Credits: Navigating New Incentives for Sustainable Growth

Esfer John Pamintuan

Senior Manager, Tax

Unlocking Green Tax Credits: Navigating New Incentives for Sustainable Growth
Scrubbed and Context Nature recently hosted a webinar called Unlocking Green Tax Credits: Navigating New Incentives for Sustainable Growth. The webinar focused on the rapidly evolving landscape of green tax credits and how companies can maximize tax incentives and savings while driving sustainability.

ACCESS THE WEBINAR

Gliezel David, Technical Accounting Group Director at Scrubbed, hosted a panel that included Ephi Banaynal dela Cruz, Co-founder and CEO of Context Nature, Sylvia Vaquer, Co-founder and CPO of Context Nature and special guest Rachel McCleery, a senior advisor in the US Department of Treasury’s Inflation Reduction Act Program Office.

What’s the Background to Green Tax Incentives?

Ephi began by explaining that the Inflation Reduction Act (IRA) of 2022 has led to investment of more than $265 billion in clean energy and helped create more than 330,000 direct and indirect jobs in the US. “The IRA’s tax incentives cover a broad range of activities. We also have cross-cutting provisions, bonuses, and new credit monetization mechanisms that apply to multiple incentives,” Rachel explained. “So, think of the IRA as a Venn diagram. And there are lots of areas where some of these credits and provisions overlap.”

Advanced Manufacturing Production Credit (45x)

The webinar focused on the new Advanced Manufacturing Production Credit (45x). This credit is designed to encourage domestic manufacturing of clean energy components. It applies to the production and sale of components such as solar panels, wind energy components, inverters, battery components, and critical minerals.

The new incentive consists of a refundable per unit tax credit for each clean energy component domestically produced and sold by a manufacturer. This is also the first time a federal tax credit has been extended to tax-exempt businesses. “We want to make sure that small business startups have access to this just like large OEMS,” says Rachel.” We are regulating it here at Treasury to ensure an increased uptake.”

The tax credit is refunded once the Treasury confirms that the business’ components are eligible and have been sold. However, companies applying for the credit must carefully examine the requirements. “Each industry and each component is going to be impacted differently,” says Rachel. “Each industry and each component is going to need different tax advice. There is no one size fits all with 45x.” Businesses in fast-growing sectors such as technology and renewable energy often rely on SaaS accounting expertise to manage the complex reporting requirements tied to these credits. 

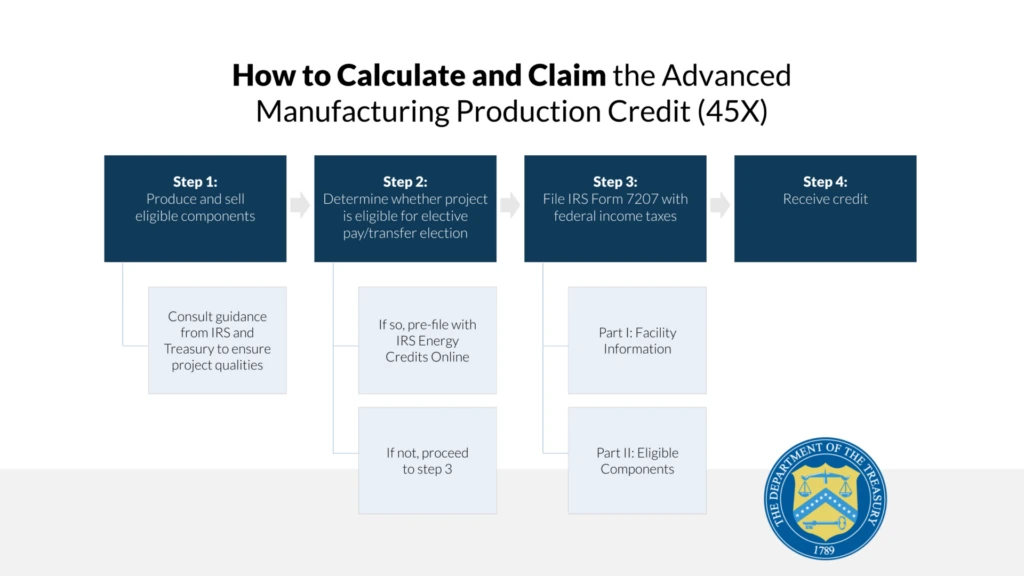
Rachel walked the attendees through calculating and claiming the credit, noting that the application process differs depending on whether a business has a tax liability. Companies without a tax liability must first create an online business account with the IRS and pre-file for energy credits. Firms with a tax liability will complete IRS Form 7202 and file it with federal income taxes.
Blog Graphics Graphs Charts 10 1024x576

Recommended Best Practices for the Advanced Manufacturing Production Credit (45X)

Rachel and Sylvia advised attendees to follow these steps to ensure the application process runs as smoothly as possible:
  • Understand Eligibility: Consult the IRS And Treasury guidance to ensure your project qualifies for the tax credit. This includes reviewing formal regulations and FAQs available on the IRS website.
  • Consult a Tax Attorney: Since the Treasury cannot provide technical assistance, firms should work with a tax attorney to understand whether a project or component qualifies for the credit.
  • Produce and Sell Eligible Components: For the Advanced Manufacturing Production Credit (45x), the company must have sold the components to qualify for the credit.
  • If Your Business Doesn’t Have a Tax Liability, Consider Credit Monetization Mechanisms: Determine whether your project is eligible for elective pay or a transfer election. This is particularly important for small businesses or startups that may not have tax liability and have to go through the online registration process with the IRS. Partnering with experts who provide fractional CFO services can help guide you through these options, ensuring you maximize available credits while staying compliant.
  • Businesses With Tax Liability File IRS Form 7207: For companies with tax liability, the credit is claimed by filing IRS Form 7207 with federal income taxes. It’s a good idea to check that the business is ready to provide all of the required information, including details about the facility and the components.

Maximizing the Credit

Sylvia then shared some of the ways that Context Nature helps their clients maximize the tax credit:
  • Understand Which Credits Apply to a Specific Business: Context Nature helps clients analyze their business data to make sure they know which credits they are eligible for and when to start the process so that they can meet required deadlines.
  • Include Additional Requirements: “There are a lot of additional requirements that can help maximize the credits, such as prevailing wage, apprenticeships, domestic content requirements,” says Sylvia. “Understanding how to navigate those can help unlock additional tax credits.”
  • Ensure Proper Documentation: Poor reporting and lack of documentation are common problems. Having the necessary evidence and supporting documentation in place reduces the risk of delay or disqualification.

Avoiding Common Errors

Just as important as the best practices and the tips to maximize the credit are the pitfalls to avoid! Rachel and Sylvia outlined some of the issues that can arise when companies apply for green tax credits:
  • Not Consulting IRS Guidance: One of the most frequent mistakes is not thoroughly consulting the IRS and Treasury guidance to ensure the project qualifies for the specific tax credit.
  • Not Getting Started in Time: Sylvia advises,” If you haven’t pre-registered or if you don’t do it in due time, then you simply miss out on the credit.” It’s important to understand when to pre-register or apply.
  • Getting the Timing Wrong: Businesses often fail to understand the importance of timing when completing the production and sale of eligible components. The tax credit can only be claimed once the company has sold the product.
  • Lack of Technical Assistance: Since the Treasury cannot provide technical assistance, businesses must rely on tax specialists to understand whether their specific project or component qualifies for the credit. Failing to do so can lead to errors in the application.
  • Improper Filing: Businesses with a tax liability must file IRS Form 7207 correctly with all required information, including facility details and eligible components. Errors in this form can lead to the IRS delaying or rejecting the refund.

Using Credits to Drive Sustainability

Green tax credits are one of the most important opportunities for businesses of all sizes to drive sustainability while maximizing financial advantages. However, the process can be challenging and successfully claiming the incentives requires careful planning, a thorough understanding of eligibility, and accurate paperwork.

Schedule a demo now on how to unlock the power of green tax credits with Context Nature’s AI-driven software—add value, save time, and scale your impact effortlessly.
Related Content

Blogs

Tax, Insurance and Cash Flow: Finance Lessons for Multi-Property Real Estate Portfolios

Tax, Insurance and Cash Flow: Finance Lessons for Multi-Property Real Estate Portfolios

The Real Estate Spotlight was one of three industry spotlights at The Future Is Fractional 2026, hosted by Scrubbed on September 24, 2026. Scrubbed partner Ejie De Jesus moderated a conversation with Geraldine Serrano, Director at Specialty Tax Group; Alex Gilmete, commercial property and casualty advisor at USI Insurance Services; and Blake Peters, founder and principal of Peters Specialty Tax Services. They covered cost segregation and bonus depreciation, R&D tax credits for real estate, insurance availability and replacement costs, and shared and layered coverage for portfolios. The short version: bring tax and insurance specialists in before decisions are made, check that your coverage reflects today’s replacement costs, and look beyond a general CPA for specialized incentives. Real estate finance is rarely one entity with one set of books. It’s multiple properties, multiple entities and often multiple jurisdictions, in a tax and risk landscape that keeps shifting. At The Future Is Fractional 2026, a virtual conference hosted by finance and accounting advisory firm Scrubbed on September 24, 2026, Session 4 split into three industry breakouts running at the same time: real estate, nonprofit and technology. In the real estate track, Scrubbed partner Ejie De Jesus brought together three specialists in cost segregation, tax incentives and commercial insurance to talk about the strategies owners most often miss. Key Takeaways: Timing is the biggest gap. Tax incentives and cost segregation are often considered after key decisions are made, when the options have already narrowed. Cost segregation accelerates depreciation. Splitting a building into shorter-lived components lets owners take larger deductions sooner, and 100% bonus depreciation, restored by 2025 tax law, can pull those deductions into year one. R&D credits reach further than most owners think. Engineering, structural and energy design work on a property may qualify. Insurance has changed fast. Some properties can’t get standard A-rated coverage, and replacement costs may have outrun policy limits. Portfolios can share coverage. A shared primary layer with excess layers on top can cost less than insuring every property to full value. Bring in specialists early, keep the decisions. Specialist advisors fill in the picture; the owner makes the call. Meet the Panel Ejie De Jesus (moderator): Partner, Scrubbed. Geraldine Serrano: Director, Specialty Tax Group, known as the “Cost Seg Queen,” specializing in cost segregation and tax strategy for real estate investors.  Alex Gilmete : Commercial Property and Casualty Advisor, USI Insurance Services, helping businesses manage and transfer risk.  Blake Peters : Founder and Principal, Peters Specialty Tax Services, specializing in R&D tax credits and other incentive programs. Timing and Visibility Gaps in Portfolio Finance Awareness comes too late. Blake Peters said the largest gap he sees is awareness. Incentives such as investment tax credits, R&D credits and energy efficiency deductions are buried in the tax code, and when owners do know about them, they’re often “looked at a little too late in the process.” Evaluating them at the start of a project can improve returns, help finance it and give investors clearer visibility. Risk has shifted fast.  Alex Gilmete said insurance has changed dramatically in just a few years. Supply chain issues, tariffs and, in California, wildfire risk have reshaped how carriers, lenders and investors view a property, and how much liability an owner carries. Property risk and insurance volatility Standard carriers, non-admitted carriers and the FAIR Plan Some properties can no longer be insured by standard A-rated carriers, Gilmete said. Location, fire exposure and crime all affect what carriers will take on. Coverage Route What The Panel Described   Standard A-rated carriers Increasingly selective; may decline older or un-upgraded buildings   Non-admitted carriers An option when standard carriers decline, at higher cost   California FAIR Plan A fallback in California when other options aren’t available That’s why Gilmete talks with investors while they’re still comparing properties. What a carrier thinks of a location affects rates and coinsurance terms (the clause that penalizes owners who insure for less than full value). He said many investors are looking at Nevada as an alternative to California, while Texas carries its own fire and flood challenges. Are you really fully insured? Gilmete warned that long-time investors may not realize how tariffs and supply chain costs have raised replacement values. A building insured for $10 million might now cost $14 million to $15 million to rebuild after a total loss, leaving the owner to cover the gap. Shared and layered coverage for portfolios Rising premiums reduce net operating income, and lower NOI lowers property value. For portfolios, Gilmete described a shared and layered approach. Take 10 properties worth $10 million each. The owner may not need $100 million of primary coverage, since a total loss on every property in one policy period is unlikely unless they share a fire or flood zone. Instead, a shared primary layer, perhaps $30 million, covers all 10, with excess layers stacked on top from different carriers. Each higher layer is less likely to be used, so it costs less per dollar of coverage. Insurance review checklist, drawn from the panel Does the policy limit reflect today’s replacement cost, not the original value? How old are the roof, HVAC, plumbing and electrical systems, and what fire suppression and egress are in place? Is everything disclosed to the carrier accurate? Carriers may inspect, and can cancel if it isn’t. How do the location’s fire, flood and crime exposure affect which carriers will quote? For a portfolio, would a shared and layered structure fit your risk tolerance? Cost Segregation: Accelerating Depreciation for Cash Flow What is cost segregation? Cost segregation is a tax strategy that separates a building’s components into shorter depreciation periods. Instead of depreciating the whole property over 27.5 years (residential rental) or 39 years (commercial), owners can deduct shorter-lived components faster, lowering current tax liability and increasing cash flow. The Lego analogy Serrano’s explanation: picture a house built of Legos. The IRS treats a residential rental as wearing out over 27.5 years. But not every piece lasts that long. Carpet, floor coverings, cabinets and countertops are five-year pieces. Driveways and landscaping are 15-year pieces. A cost segregation study takes the house apart and sorts the shorter-lived pieces into their own buckets. Bonus depreciation under the One Big Beautiful Bill Act The One Big Beautiful Bill Act, signed in July 2025, restored 100% bonus depreciation and made it permanent for qualifying property acquired after January 19, 2025. Combined with cost segregation, that lets owners deduct the full cost of those shorter-lived components in the first year. Serrano told the story of a client she called “Mr. I Hate the IRS,” who was about to mail a $100,000 check to the IRS. Cost segregation studies on his 12 Denver-area rentals eliminated the liability. His CPA hadn’t recommended it because she believed it applied only to commercial property. Results depend on the owner's situation. Rules on passive rental losses and depreciation recapture when a property is sold can change the math. She also pointed to manufacturers. A newer provision allows qualifying manufacturing buildings to be fully expensed rather than depreciated, so those owners may not need a cost segregation study at all. Before or after construction? Before, Serrano said. “The sooner we talk about the project, the better.” She cited an owner who built an Oakland office from shipping containers and welded them together because it was cheaper. Bolting them, so they could be taken apart, might have qualified far more of the building as five-year property. That may not have changed his choice, but he would have made it knowing the tax impact. He also demolished an existing structure without his CPA setting up a general asset account, and missed a tax benefit as a result. For cost segregation, she noted, what matters is when a building was bought and placed in service, not its age. Insurers look at age. Planning has to account for both. R&D Tax Credits for Real Estate and Construction Peters called the R&D credit “one of the worst named credits out there.” For tax purposes, it can cover work involving analysis, alternatives and design, not just scientists and software. In real estate, that can include: Engineers evaluating structural methods depending on contract terms HVAC and energy design to meet efficiency or LEED requirements Custom engineering to improve a building’s performance Manufacturers building capital-intensive facilities Investment in AI, built in-house or subcontracted, across industries His advice: don’t ask “do we do R&D?” Ask where the money and effort are going. What changed recently. From 2022 through 2024, research expenses had to be spread over five years or more instead of deducted right away, research expenses had to be amortized rather than deducted right away, which made the credit less attractive. Peters said the One Big Beautiful Bill Act fixed that going forward and, for some businesses, retroactively. Companies that stopped claiming the credit should reassess. Cost segregation vs. the R&D tax credit. Header Header R&D Tax Credit What it does Accelerates deductions, which lower taxable income A credit that reduces the tax owed dollar for dollar What can qualify, per the panel Shorter-lived components: flooring, cabinets, countertops, driveways, landscaping Structural engineering, HVAC and energy design, custom building systems, capital-intensive facilities When to look Before construction or acquisition decisions At the front end of a project Overlap - Custom HVAC and energy work often touch both, so owners can address them together Capital Improvements: Tax benefit and Insurability Do roof or HVAC upgrades lower insurance costs? Not directly, Gilmete said. But major carriers may refuse to quote older buildings that haven’t been upgraded. He described a Santa Clara property where the roof had to be replaced before A-rated carriers would consider it. On the tax side, Peters said custom engineering for HVAC or energy performance can qualify for the R&D credit. Keep the Decisions, Bring in the Experts The panel’s closing advice was about what to keep in-house. General CPAs may be excellent but lack this level of specialization. Serrano offers clients a second review by another CPA when their current CPA is unfamiliar with cost segregation. Bringing in specialists early to review tax incentives, cost segregation, contracts, insurance policies and risk tolerance lets the owner decide with a full picture. As Gilmete put it, the experts “fill out your dashboard, and then the owner gets to make decisions based on that dashboard.” This session is part of TFIF 2026.  To see how planning connects to talent, AI and team design, read, read Own the Core, Access the Rest: What The Future is Fractional (TFIF) 2026 Revealed About How Finance Teams Are Being Rebuilt   what finance leaders are rethinking about talent, AI and team structure.

Read More >
Blogs

September 15 Estimated Tax Deadline: Strategies for Pass-Through Entities

September 15 Estimated Tax Deadline: Strategies for Pass-Through Entities

For growing pass-through entities, the September 15 tax deadline often creates a collision between cash flow and internal capacity. Guessing at estimated payments leaves companies vulnerable to IRS penalties or unnecessarily traps critical working capital meant for Q4 growth. By establishing a Safe Harbor floor and utilizing the Annualized Income Installment Method, companies can align tax outlays directly with actual revenue. When this execution is handled proactively, finance leaders stop playing defense against deadlines and reclaim their time for strategic planning. When a high-growth pass-through entity, such as an S-Corp or a Partnership, comes off an unexpectedly strong summer, revenue is up. This should be a moment for leadership to celebrate and plan their Q4 investments. Instead, the internal finance team often finds themselves staring down a cash crunch they didn't anticipate. The pressure point is September 15. For growing operations, this date is often a collision course. It is not only the deadline for Q3 estimated tax payments, but it is also the extended filing deadline for Forms 1065 and 1120-S . When you have an internal team trying to finalize the previous year's historical data while simultaneously projecting the current year's performance, the structure usually begins to strain. This isn't about a team dropping the ball. It's simply what happens when internal workflows haven't scaled up to match a company's growth. When two major deadlines collide, and the volume is too high, a stretched team has no choice but to improvise. The Cost of "Guesstimating" In a pass-through entity, the business itself generally does not pay federal income tax. Because income from partnerships and S corporations generally passes through to their owners, owners may need to make individual estimated tax payments based in part on their share of the entity’s taxable income When internal teams don't have a dedicated workflow for this, they often get bogged down trying to predict exact year-end profits during a busy quarter. Without a clear mechanism to manage this, I frequently see companies do one of two things: they either underpay and leave themselves vulnerable to IRS penalties, or they overpay to "be safe." Overpaying might feel like the responsible choice in the moment, but it unnecessarily ties up working capital. When these distributions are sized off gross revenue rather than a projection that accounts for deductions or state-level elections, the company pulls more cash out of the operating account than the owners actually owe. That excess traps liquidity that could have been used to fund critical Q4 growth initiatives—like a marketing push or inventory expansion—without seeking outside financing. Establishing an Estimated-Tax Safe Harbor  When our tax professionals step in to manage this process, the very first thing we do is establish a predictable foundation. We immediately build a "Tax Compliance Calendar" integrated with a "Safe Harbor Floor." A useful starting point is determining which estimated-tax safe harbor applies. For many taxpayers, one option is to base required annual payments on 100% of the prior year's tax, increasing to 110% for certain higher-income taxpayers. The current-year 90% test may also apply. Meeting the applicable requirements through timely payments can generally reduce exposure to estimated-tax underpayment penalties. Once that floor is established, we can adjust for the reality of the current year. Aligning Outlays with Actual Cash Flow If a company sees a massive spike in revenue during Q3, the standard installment method might demand a payment that creates a sudden cash flow imbalance. Good intentions won't balance the cash flow at this stage; you need a precise mathematical approach. To stabilize cash flow during a sudden revenue surge, one strategy to consider is the Annualized Income Installment Method . Instead of assuming income is earned evenly throughout the year, the Annualized Income Installment Method determines the owner's required installments based more closely on income earned during the applicable annualization periods State-level PTE tax elections may also provide federal tax benefits by allowing qualifying state income taxes to be paid and deducted at the entity level rather than being subject to the individual SALT deduction limitation. The result? Depending on the state's PTE tax regime, entity-level payments may reduce the state estimated-tax payments otherwise required from individual owners. A deductible PTE tax payment may also reduce the taxable income passed through to owners for federal purposes, which can affect their projected federal estimated-tax liability. Restoring Strategic Headspace When tax planning is handled consistently throughout the year, it changes how a leadership team operates. It can significantly reduce the risk of an "April Surprise." When Q3 estimates are calculated accurately and tied to a deliberate strategy, leadership knows exactly how much capital is truly theirs to spend. Tax shifts from a looming, unpredictable liability into a manageable line item. Just as importantly, the internal finance leader gets their time back. Instead of spending the first two weeks of September finalizing and issuing K-1s, calculating thresholds, and worrying about penalties, they can focus on high-level financial modeling and operational efficiency. A strong tax partner doesn't just run the numbers; they take the friction out of the process so your team can focus forward. When an experienced team handles the heavy lifting behind the scenes, you stop playing defense against IRS deadlines and start using tax strategy as a genuine tool to fund your growth. See how our tax professionals support growing operations and keep execution predictable. Let's talk through how we can support your finance function. Comparing Q3 Tax Strategies: Safe Harbor vs. Annualized Method vs. PTE Strategy Ideal for Primary Benefit Risk Level  100%/110% Safe Harbor  Rapidly growing companies  Provides protection from estimated-tax underpayment penalties when applicable safe-harbor requirements are satisfied  Low (May temporarily tie up cash if revenue drops)  Annualized Method  Seasonal or late-year spiking revenue Align tax outlays directly with timing of taxable income  Moderate (Requires meticulous record-keeping) PTE Tax Election Entities in high-tax states May provide an entity-level federal deduction for qualifying state income taxes while providing state tax benefits to eligible owners Low (Requires state-specific eligibility and election compliance) Key Takeaways: The Deadline Collision: The simultaneous timing of Q3 estimates and extended historical filings places severe strain on internal finance teams when workflows haven't scaled. The Cost of "Guesstimating": Overpaying estimated taxes based on gross revenue ties up liquidity that could otherwise fund critical Q4 growth initiatives without requiring outside financing. Building a Safe Harbor Floor: Establishing a baseline payment based on 100% or 110% of the prior year's tax liability can provide protection from estimated-tax underpayment penalties when the applicable safe-harbor requirements are satisfied. Aligning Cash Flow: The Annualized Income Installment Method stabilizes cash positions by calculating tax based on income earned during the applicable annualization periods rather than an arbitrary quarterly fraction. Restoring Strategic Headspace: When tax planning is handled reliably behind the scenes, internal finance leaders get their time back to focus on high-level financial modeling instead of chasing K-1s.

Read More >
Blogs

Decoding the Digital Ledger: Navigating FASB’s New Standards for Crypto Assets and Intangibles (ASU 2023-08)

Decoding the Digital Ledger: Navigating FASB’s New Standards for Crypto Assets and Intangibles (ASU 2023-08)

In a groundbreaking move reflecting the swift evolution of the financial landscape, the Financial Accounting Standards Board (FASB) has taken a significant step with the release of the final Accounting Standards Update (ASU) 2023-08 titled “Accounting for and Disclosure of Crypto Assets.” This authoritative guidance specifically addresses Crypto Assets within the Intangibles—Goodwill and Other category, marking a crucial advance in establishing standardized accounting practices for these assets. Bridging the Gap: A Brief Background The rise of digital assets, from cryptocurrencies like Bitcoin and Ethereum to unique non-fungible tokens (NFTs), has challenged traditional accounting norms. Without specific Generally Accepted Accounting Principles (GAAP) guidance, accounting professionals relied on analogies and interpretations, resulting in a diverse patchwork of practices.  Our article “Rise of Digital Assets in Business” explored the evolving landscape, highlighting the AICPA Practice Aid titled “Accounting for and Auditing of Digital Assets” as a crucial guide within the constraints of the existing accounting framework. We are witnessing a groundbreaking shift with the finalized FASB’s ASU on Crypto Assets, effective December 15, 2024, which will change how the world sees crypto assets. Who Will Be Affected? The new ASU applies to a wider range of entities than you might think. Any entity holding crypto assets that meet specific criteria will be impacted. These criteria include: Meet the definition of an intangible asset. Do not grant enforceable rights or claims on underlying goods, services, or assets. Exist on a blockchain-based distributed ledger or similar technology. Are secured using cryptography. Are fungible. Are not created or issued by the reporting entity or its related parties. Crypto assets falling within these criteria must be measured at fair value, with changes in value recognized in their income statement each reporting period. Moreover, transaction costs incurred in acquiring these assets, such as commissions and related fees, will be expensed unless other industry-specific guidance dictates otherwise. A Closer Look at the New ASU  Mandating Relevance: Fair Value Measurement  The update mandates the fair value measurement of crypto assets at each reporting period. This focus on fair value measurement stems from the belief that fair value offers investors more relevant information about the assets’ sale value and changes in that value. The Board rejected historical cost and net realizable value as alternatives due to limitations in reflecting downward and upward price movements. The existing guidance in Topic 820 was deemed sufficient for fair value measurement, given its applicability to other assets and current use by reporting entities. As financial reporting evolves, organizations offering ESG reporting services may also need to consider how such valuation updates intersect with broader transparency and sustainability disclosure requirements. Beyond Annual Assessment: Recognizing Both Gains and Losses Unlike the existing ASC 350 model, which mandates an annual assessment of crypto asset value that only recognizes gains upon sale, the update embraces a more dynamic approach. The new method captures both negative and positive market movements, addressing longstanding concerns about the traditional model’s failure to reflect the true and current economic nature of crypto assets at each reporting period. As well as providing a more comprehensive understanding of the underlying economics and an entity’s financial position, the shift signifies a progressive step toward a more responsive and accurate representation of the financial impact of market fluctuations on digital holdings. Enhancing Transparency: Disclosure Requirements The ASU prioritizes transparency, incorporating detailed disclosure requirements for asset categorization, impairment considerations, and, notably, the separate presentation of crypto assets from other intangible assets in the statement of financial position. Entities must disclose the following for annual and interim reporting periods: 1. Details of significant and less significant crypto asset holdings, including name, cost basis, fair value, and quantity. 2. Information on restricted crypto assets, covering fair value, nature, the remaining duration of restrictions, and circumstances for the potential lapse. For annual reporting periods, additional disclosures are required: 1. A roll forward of crypto asset activity, including additions, dispositions, gains, and losses. Specify the income statement line item for unrecognized gains and losses if not presented separately. 2. Detail dispositions of crypto assets, including sale price, cost basis difference, and relevant activities. 3. The method used to determine the cost basis of crypto assets. These changes enhance transparency and understanding of crypto asset holdings, ensuring comprehensive disclosure for annual and interim reporting periods. Nevertheless, entities immediately converting crypto assets received as noncash consideration or contributions into cash are exempt from the above annual additional disclosures. The Countdown Begins: Timeline and Adoption The final standard takes effect for all entities in reporting periods beginning after December 15, 2024, including interim periods within those fiscal years. Early adoption is permitted, allowing entities to embrace the changes ahead of the mandated timeline. However, early adopters must use a modified retrospective approach, requiring recording a cumulative effect adjustment to equity (or net assets) from the commencement of the adoption year. What Lies Ahead: Implications for the Future The issuance of the finalized ASU 2023-08 represents a proactive response to the growing significance of crypto assets in today’s financial landscape. The finalized ASU is a significant milestone in our journey toward a standardized and transparent future for crypto asset accounting, offering consistency in financial reporting across diverse industries engaged with crypto assets. The FASB’s move acknowledges the need for accounting standards that keep pace with technological advancements and reflect the realities of the modern economy. Stay tuned for further developments. How Scrubbed Can Help You? Navigating the opportunities and challenges of crypto assets demands expertise, whether you’re an individual investor or a business. At Scrubbed, our comprehensive range of services empowers you to stay ahead: • Compliance Experts: Navigate crypto regulations effortlessly with our seasoned professionals. From taxes to reporting, we’ve got your compliance needs covered. • Rock-Solid Controls: Establish secure systems and ensure compliance with the latest financial reporting standards like GAAP and IFRS. • Innovative Strategies: Beyond the numbers, we offer strategic insights about market tren ds and help you make wise decisions. As we collectively pioneer a new era of financial reporting, Scrubbed is committed to bridging the gap between traditional accounting norms and the groundbreaking shifts introduced by the FASB on Crypto Assets. Our Technical Accounting Group is ready to assist your business in decoding the digital ledger, ensuring effective operations, and maintaining compliance with evolving regulations. We also provide specialized biotech accounting services, supporting organizations in highly regulated industries with tailored financial reporting solutions. For a comprehensive consultancy assessment tailored to your specific needs, reach out to [email protected].

Read More >

Contact Information

SF Bay Area Headquarters
111 Anza Boulevard, Suite 320, Burlingame, CA 94010, United States

Phone: (800)837-5160
Email: [email protected]

"Scrubbed" is the brand name under which Scrubbed Advisory, LLC and Scrubbed Assurance, LLP provide professional services. Scrubbed Advisory, LLC and Scrubbed Assurance, LLP practice in an alternative practice structure in accordance with the AICPA Code of Professional Conduct and applicable law, regulations, and professional standards. Scrubbed Assurance, LLP is a licensed independent CPA firm that provides attest services to its clients, and Scrubbed Advisory, LLC provides tax, finance, and support services to its clients. Scrubbed Advisory, LLC is not a licensed CPA firm.

Copyright © Scrubbed. All rights reserved.