How ESG Movement Affects Your Accounting and Financial Reporting

John Mark Respeto

Sustainability and Quality Director

How ESG Movement Affects Your Accounting and Financial Reporting
By now most of us are familiar with the concept of Environmental, Social, and Governance (ESG)—three key factors in measuring a company’s sustainability and its ethical and social impact. Businesses that focus on ESG are better equipped to sustain long-term value, reduce their carbon footprint, manage risks, and capitalize on opportunities.

While it might not be readily apparent, ESG has a direct impact on your accounting and financial reporting. With a greater understanding of how ESG impacts your business from an accounting perspective, you can take steps to meet emerging requirements and standards.

The Undeniable Move Toward ESG

Companies across the globe are committing to take greater responsibility for combatting the climate change crisis. The Paris Agreement has secured commitments from many countries worldwide, all pledging to take substantive actions to reduce their greenhouse gas emissions to as close to zero as possible and achieve a climate neutral world by 2050. 

While the environmental focus of ESG is critical, social impact is just as important. Many employees today prefer to work for companies that are guided by socially responsible practices, and consumers and businesses alike want to buy from companies they view as ethical and responsible. 

An emphasis on ESG is spurring more businesses to recalibrate their focus, priorities, strategies, and plans. At the same time, ESG is fast becoming another framework for anyone in a business’s ecosystem—including employees, regulators, customers, and investors—to assess the company’s performance aside from its financials.
ESG 01 1 2048x706

How ESG Impacts Accounting and Financials

As a McKinsey report noted, companies that commit to ESG practices experience higher growth, lower costs, increased productivity, and fewer regulatory and legal interventions. While adopting ESG practices isn’t mandatory yet, there is a sense that it could become a requirement at some point. Even without such mandates, integrating an ESG framework into the operation will surely be essential for companies that expect to grow and thrive.

In fact, the many stakeholders that impact a business’s success increasingly expect companies to follow ESG practices. That includes investors, customers, legislators, the media, and anyone else within a business’s ecosystem. As these stakeholders “vote with their wallets” by purchasing sustainable products and services and investing in values-based companies, regulators are responding with efforts to standardize ESG reporting frameworks. This shift has a direct impact on a business’s accounting, making ESG reporting services and even highly specialized support like biotech accounting services essential for ensuring accurate, transparent, and compliant disclosures.

Companies are already beginning to account for items that arise out of ESG practices within their financial statements, even in the absence of standards or requirements, though doing so is far from straightforward. For example, if your business has ESG assets such as carbon offsets (including Renewable Energy Credits, or RECs), green bonds, or other financial instruments associated with ESG, it adds complexity to your accounting. It’s critical to understand the nature of ESG-related assets, acceptable accounting practices, and emerging standards and regulations.

Taxation is one area of accounting where ESG can have a big impact. Often, governments allow tax credits or assess tax penalties related to a company’s adoption (or failure to adopt) sustainable, environmentally sound practices. For instance, the Inflation Reduction Act in the US, passed in August 2022, provides production tax credits for solar energy companies, investment tax credits for energy storage technologies, and many other clean energy tax provisions. It’s vital to know whether your business is eligible for ESG-related tax credits and how they might affect your financials. 

Financial reporting also is significantly impacted by ESG, with emerging regulatory standards and guidance that will require companies to improve their financial controls and ESG data analytics processes. And from an audit perspective, businesses will need to provide some degree of assurance and confidence in the reliability and credibility of their ESG reporting. 

A Closer Look at ESG Reporting Standards

Given the complexity of ESG reporting, regulators worldwide are hard at work establishing standards or guidance to help companies report on their ESG activities in a way that is relevant and provides a faithful representation of both their commitments and their progress toward meeting them. 

Several regulatory proposals would require companies to disclose information about each of the three main sources of greenhouse gas emissions: Scope 1 (a business’s direct emissions), Scope 2 (emissions a company makes indirectly, for example, through the energy a third party generates for its use), and Scope 3 (emissions from the business’s value chain).

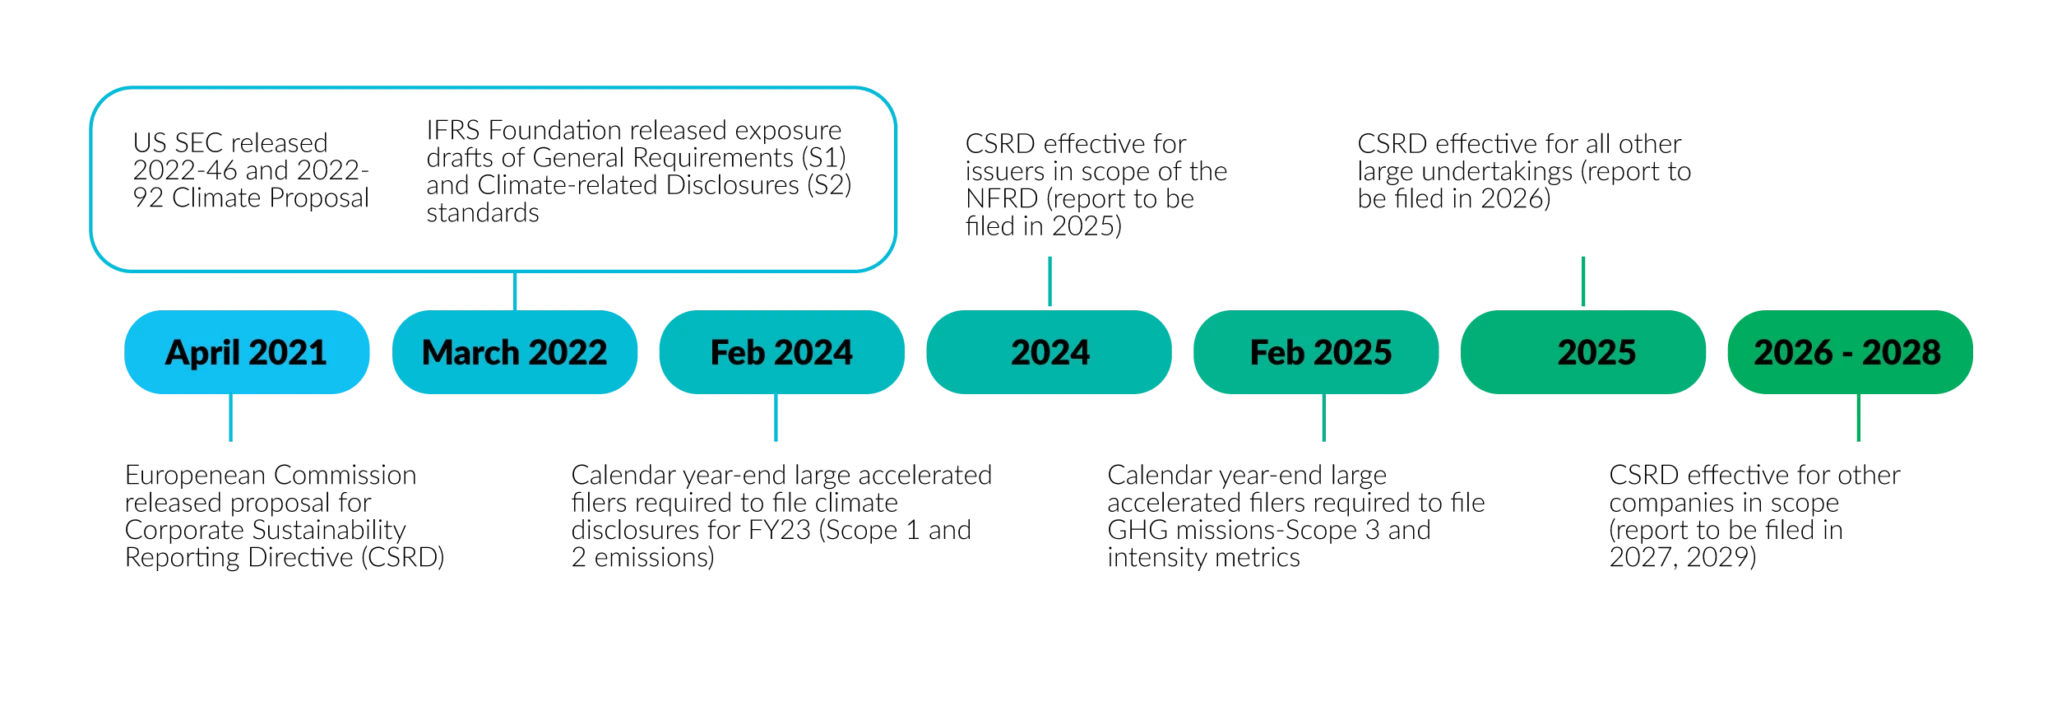
On a global level, the International Sustainability Standards Board (ISSB), established in late 2021 during the United Nations’ climate change conference, is developing a baseline of disclosure standards to ensure stakeholders can obtain information about a business’s sustainability-related risks and opportunities. Referred to as the IFRS Sustainability Disclosure Standards, they were released in March 2022 in two exposure drafts: IFRS S1 covers general requirements for disclosing sustainability-related financial information, while IFRS S2 focuses on climate-related disclosures.

In the US, the Securities and Exchange Commission (SEC), which has provided guidance on climate change-related disclosures for over a decade, is now working to further improve sustainability reporting. In March 2022, the SEC released two proposals related to climate change reporting—one for public companies, the other for ESG funds.

And in Europe, regulators have already pushed to adopt the Corporate Sustainability Reporting Directive (CSRD), which supports the European Green Deal climate change initiatives and extends previous directives to include more European and non-European companies listed and operating in the EU-regulated markets. The directive requires companies to comply with amended reporting requirements beginning in 2024 if they are already in scope of the EU’s Non-Financial Reporting Directive (NFRD), in line with mandatory EU sustainability reporting standards and alongside an external assurance of sustainability reporting. To help companies comply, the European Commission released background on corporate sustainability reporting and the CSRD proposal. 
How Scrubbed Can Support Your ESG Accounting

The Technical Accounting team at Scrubbed is committed to staying on top of new developments and regulatory changes that impact your accounting and finance operations. That includes keeping current on the rapidly evolving ESG landscape. The Scrubbed team is deeply knowledgeable about how ESG affects your accounting and financial reporting and is ready to help you with ESG-related disclosure compliance, reporting, tax, data analytics, and assurance support. Contact Scrubbed to learn how we can help you meet changing and emerging ESG accounting and reporting requirements.  Keep an eye out for more information about ESG accounting and finance, including an upcoming blog on green accounting!

Need to make ESG reporting more reliable?


Speak with Scrubbed about the data, workflows, and documentation your stakeholders expect.

TALK TO A SCRUBBED EXPERT
Need to make ESG reporting more reliable

Related Content

Blogs

7 Numbers Boutique Hotel Owners Should Be Looking At Every Month

7 Numbers Boutique Hotel Owners Should Be Looking At Every Month

Boutique hotel owners don't need to review every line of a monthly financial package to understand how the business is performing. Seven numbers tell most of the story: occupancy, average daily rate (ADR), RevPAR, total revenue, labor costs and productivity, gross operating profit (GOP), and cash. Reviewed together and consistently, they show whether a hotel is pricing rooms well, controlling its largest costs, and generating cash it can actually use. Hotel owners have a lot of numbers coming at them every month. Night audit reports, benchmarking data, P&L statements, labor reports, and bank balances all compete for attention. You don't need to look at everything to know how the business is doing. I've spent more than a decade in hotel finance, from a two-person accounting team at a newly opened boutique hotel to finance leadership roles at Hilton, The Redbury Hotel, and Avalon Hotel Beverly Hills. Across all of them, a handful of numbers, reviewed consistently, told me most of what I needed to know. This matters even more for independent and boutique properties. Many don't have a brand's corporate finance support or a dedicated asset manager, so the owner is often the one who has to notice what changed and ask why. Having co-founded a hospitality company myself, I know how much of that lands on the owner's desk. Here are the seven I think are worth paying attention to. What do occupancy, ADR, and RevPAR tell hotel owners? Occupancy, ADR, and RevPAR measure how well a hotel sells its rooms. Occupancy shows how many rooms you filled. ADR shows what guests paid for them. RevPAR combines the two into one number. Read together, they show whether room revenue is growing through volume, price, or both, and which approach is working. 1. Occupancy Occupancy is the percentage of available rooms sold during a period. It is calculated as rooms sold divided by rooms available. Occupancy drives almost every part of hotel spending. It affects how many housekeepers you schedule, how many operating supplies you use, your utility bills, and even sales in other departments. Every occupied room is also an opportunity to earn more than the room rate, through a dinner reservation, a parking fee, or an event booking. 2. Average Daily Rate (ADR) ADR is the average price guests pay per occupied room. It is calculated as room revenue divided by rooms sold. Higher occupancy is not always better. Every occupied room carries a cost: labor for cleaning, guest amenities, laundry, and utilities. ADR determines how much of each room sale is left after those costs are covered. A stronger rate on the same cost base sends more money to the bottom line. 3. RevPAR Revenue per available room (RevPAR) is calculated as room revenue divided by rooms available, or occupancy multiplied by ADR. It shows the balance between filling rooms and pricing them well. Selling out is not always the goal. Consider a 100-room hotel on a single night: Scenario Occupancy ADR Room Revenue RevPAR Rooms  A  80%  $150  $12,000  $120  80  B  70%  $180  $12,600  $126 70 Scenario B earns more room revenue while servicing 10 fewer rooms. That means lower housekeeping, laundry, and amenity costs on top of the higher revenue. This is why it's worth comparing your RevPAR against your competitive set, typically through benchmarking reports such as STR, rather than chasing a full house. Why should hotel owners look beyond revenue? Total Gross Operating Revenue is only part of a hotel's overall story. While it is important to bring in as much revenue as possible, it is equally important to understand and manage expenses based on forecasted occupancy and income. A property’s operating budget is the initial plan for any given period, but the management team must be ready to adapt when necessary. One of the best metrics to use when budgeting and forecasting is Cost Per Occupied Room (CPOR).  4. Cost Per Occupied Room Cost Per Occupied Room is one of the most effective ways to analyze and forecast expenses in the hotel industry due to its direct relation to usage and consumption by hotel guests. To  achieve ideal profit margins on a monthly basis, variable expenses should be adjusted to maintain the budgeted proportionate spend.  For example, if Guest Amenities are budgeted at a total of $4.50 per occupied room, the finance leader can easily reduce allowed spending $4.50 for every room that falls short to budget. In a month where forecasted occupied rooms are expected to finish below expected occupancy by 300 rooms, the adjusted spend in Guest Amenities for that month can be reduced by $1,350.00 compared to budget. In the opposite scenario, if anticipated occupancy exceeds budget by 300 rooms, the Controller or Director of Finance can hypothetically increase spend by up to $1,350.00 if required to maximize guest experience without sacrificing profit margins.  Which costs have the biggest impact on hotel profitability? Labor is the largest operating expense for most hotels, which makes it the first place to look for profit opportunities. Pairing labor costs with productivity measures, then tracking gross operating profit (GOP), shows whether revenue is actually turning into profit. A busy hotel and a profitable hotel are not always the same thing. 5. Labor Costs and Productivity Track labor in two ways: total cost and productivity. Total cost shows what you spent. Productivity shows whether the hours you scheduled matched the business you actually had. Common productivity measures include housekeeping minutes per occupied room and labor cost per occupied room. Know your target for each, and build schedules from forecasted occupancy rather than last month's schedule. When occupancy dips midweek, hours should follow. When I managed accounting for seven hotels at once, labor productivity reports were part of every monthly package. Seeing properties side by side made it clear how quickly hours drift when schedules aren't tied to the forecast. 6. Gross Operating Profit (GOP) GOP is total revenue minus departmental expenses and undistributed operating expenses, such as administrative and general, sales and marketing, maintenance, and utilities. These categories follow the Uniform System of Accounts for the Lodging Industry (USALI), the standard reporting framework used across the hotel industry. Any management company or asset management team will stress the importance of achieving GOP. If the hotel is falling short of its revenue forecast, expenses should be adjusted so the team still reaches its profit margin goal. Tracking GOP margin (GOP as a percentage of total revenue) and GOPPAR (GOP per available room) makes month-to-month comparisons easier. Every month, I prepared a financial critique for ownership that explained the major variances to budget. It's a habit any owner can borrow: if GOP falls short, you should be able to say which lines moved and why. Why is cash different from profit for a hotel? A hotel can show a profit on its income statement and still run short of cash. Payroll, vendor payments, repairs, taxes, and capital improvements all draw on cash, often on a different schedule than revenue comes in. Owners need to know both what is in the bank today and what the coming months will require. 7. Cash Flow Profit on paper is one thing. Having enough cash for payroll, vendors, repairs, taxes, and upcoming improvements is another. A few hotel-specific items deserve attention. Occupancy taxes collected from guests belong to the taxing authority, so that balance isn't yours to spend. Seasonal properties need to set aside cash for slower months while revenue is still strong. Furniture, fixtures, and equipment (FF&E) also wear out on a predictable cycle, which is why many hotels fund a replacement reserve, often around 3% to 5% of total revenue. Early in my career, I produced daily and weekly cash flow forecasts for multiple hotels. Later, I set up the front desk and accounting cash handling process for a new property. Both taught me the same lesson: cash needs its own attention, separate from the P&L. Look ahead, not just at today's balance. A rolling 13-week cash forecast is a simple way to see what's coming before it arrives. How should boutique hotel owners review these numbers each month? Monthly financials don't need to be complicated. Review the same seven numbers at the same time each month, and compare them against budget, the same month last year, and your competitive set. The goal is not to analyze everything. It's to notice when something changes and ask why before it becomes a bigger problem. A simple monthly routine looks like this: Compare each number to budget and to the same month last year. Look for numbers that should move together but don't, such as occupancy rising while labor productivity falls. Flag anything that doesn't look right and ask your finance team or accountant to explain it. For smaller and independent hotels, what matters is having a few numbers you understand, reviewing them consistently, and asking questions when something doesn't look right. Sometimes the most useful conversation with your accountant starts with just a few numbers. The 7 monthly numbers Metric What is measures How to calculate Question to ask each month  Occupancy  Share of available Rooms sold ÷ rooms available Are we filling rooms at the pace we forecasted?  ADR  Average price paid per occupied room Room revenue ÷ rooms sold  Is our rate in line with demand and our competitive set?  RevPAR  Room revenue earned per available room Room revenue ÷ rooms available How do we compare with our competitive set?  Cost Per Occupied Room (CPOR) The average of spend for any rooms related expense based on each occupied room Total expense ÷ Total occupied rooms  How can I adjust my expenses based on current forecasted occupancy?  Labor costs and productivity  Labor spend and how efficiently hours are used Labor cost ÷ occupied rooms; minutes per occupied room Did scheduled hours match actual occupancy?  GOP  Profit from hotel operations before fixed charges Total revenue - departmental and undistributed expenses Is revenue turning into profit at our target margin?  Cash  Money available to run and maintain the hotel  Current balance + expected inflows - expected outflows Can we cover the next 13 weeks of obligations? Key Takeaways Read room metrics together: Occupancy, ADR, and RevPAR each tell part of the story. Together they show whether revenue is growing through volume, price, or both. Full doesn't always mean better: A hotel can earn more room revenue with fewer occupied rooms when its rate is stronger, and spend less to service them. Look at the whole property: Food and beverage, parking, and events can drive meaningful revenue, especially for boutique hotels. Start with labor: As the largest operating expense, labor is where schedule discipline has the most direct effect on GOP. Plan cash ahead: Profit doesn't pay payroll. A forward-looking cash forecast keeps payroll, taxes, and improvements covered.

Read More >
Blogs

Decoding the Digital Ledger: Navigating FASB’s New Standards for Crypto Assets and Intangibles (ASU 2023-08)

Decoding the Digital Ledger: Navigating FASB’s New Standards for Crypto Assets and Intangibles (ASU 2023-08)

In a groundbreaking move reflecting the swift evolution of the financial landscape, the Financial Accounting Standards Board (FASB) has taken a significant step with the release of the final Accounting Standards Update (ASU) 2023-08 titled “Accounting for and Disclosure of Crypto Assets.” This authoritative guidance specifically addresses Crypto Assets within the Intangibles—Goodwill and Other category, marking a crucial advance in establishing standardized accounting practices for these assets. Bridging the Gap: A Brief Background The rise of digital assets, from cryptocurrencies like Bitcoin and Ethereum to unique non-fungible tokens (NFTs), has challenged traditional accounting norms. Without specific Generally Accepted Accounting Principles (GAAP) guidance, accounting professionals relied on analogies and interpretations, resulting in a diverse patchwork of practices.  Our article “Rise of Digital Assets in Business” explored the evolving landscape, highlighting the AICPA Practice Aid titled “Accounting for and Auditing of Digital Assets” as a crucial guide within the constraints of the existing accounting framework. We are witnessing a groundbreaking shift with the finalized FASB’s ASU on Crypto Assets, effective December 15, 2024, which will change how the world sees crypto assets. Who Will Be Affected? The new ASU applies to a wider range of entities than you might think. Any entity holding crypto assets that meet specific criteria will be impacted. These criteria include: Meet the definition of an intangible asset. Do not grant enforceable rights or claims on underlying goods, services, or assets. Exist on a blockchain-based distributed ledger or similar technology. Are secured using cryptography. Are fungible. Are not created or issued by the reporting entity or its related parties. Crypto assets falling within these criteria must be measured at fair value, with changes in value recognized in their income statement each reporting period. Moreover, transaction costs incurred in acquiring these assets, such as commissions and related fees, will be expensed unless other industry-specific guidance dictates otherwise. A Closer Look at the New ASU  Mandating Relevance: Fair Value Measurement  The update mandates the fair value measurement of crypto assets at each reporting period. This focus on fair value measurement stems from the belief that fair value offers investors more relevant information about the assets’ sale value and changes in that value. The Board rejected historical cost and net realizable value as alternatives due to limitations in reflecting downward and upward price movements. The existing guidance in Topic 820 was deemed sufficient for fair value measurement, given its applicability to other assets and current use by reporting entities. As financial reporting evolves, organizations offering ESG reporting services may also need to consider how such valuation updates intersect with broader transparency and sustainability disclosure requirements. Beyond Annual Assessment: Recognizing Both Gains and Losses Unlike the existing ASC 350 model, which mandates an annual assessment of crypto asset value that only recognizes gains upon sale, the update embraces a more dynamic approach. The new method captures both negative and positive market movements, addressing longstanding concerns about the traditional model’s failure to reflect the true and current economic nature of crypto assets at each reporting period. As well as providing a more comprehensive understanding of the underlying economics and an entity’s financial position, the shift signifies a progressive step toward a more responsive and accurate representation of the financial impact of market fluctuations on digital holdings. Enhancing Transparency: Disclosure Requirements The ASU prioritizes transparency, incorporating detailed disclosure requirements for asset categorization, impairment considerations, and, notably, the separate presentation of crypto assets from other intangible assets in the statement of financial position. Entities must disclose the following for annual and interim reporting periods: 1. Details of significant and less significant crypto asset holdings, including name, cost basis, fair value, and quantity. 2. Information on restricted crypto assets, covering fair value, nature, the remaining duration of restrictions, and circumstances for the potential lapse. For annual reporting periods, additional disclosures are required: 1. A roll forward of crypto asset activity, including additions, dispositions, gains, and losses. Specify the income statement line item for unrecognized gains and losses if not presented separately. 2. Detail dispositions of crypto assets, including sale price, cost basis difference, and relevant activities. 3. The method used to determine the cost basis of crypto assets. These changes enhance transparency and understanding of crypto asset holdings, ensuring comprehensive disclosure for annual and interim reporting periods. Nevertheless, entities immediately converting crypto assets received as noncash consideration or contributions into cash are exempt from the above annual additional disclosures. The Countdown Begins: Timeline and Adoption The final standard takes effect for all entities in reporting periods beginning after December 15, 2024, including interim periods within those fiscal years. Early adoption is permitted, allowing entities to embrace the changes ahead of the mandated timeline. However, early adopters must use a modified retrospective approach, requiring recording a cumulative effect adjustment to equity (or net assets) from the commencement of the adoption year. What Lies Ahead: Implications for the Future The issuance of the finalized ASU 2023-08 represents a proactive response to the growing significance of crypto assets in today’s financial landscape. The finalized ASU is a significant milestone in our journey toward a standardized and transparent future for crypto asset accounting, offering consistency in financial reporting across diverse industries engaged with crypto assets. The FASB’s move acknowledges the need for accounting standards that keep pace with technological advancements and reflect the realities of the modern economy. Stay tuned for further developments. How Scrubbed Can Help You? Navigating the opportunities and challenges of crypto assets demands expertise, whether you’re an individual investor or a business. At Scrubbed, our comprehensive range of services empowers you to stay ahead: • Compliance Experts: Navigate crypto regulations effortlessly with our seasoned professionals. From taxes to reporting, we’ve got your compliance needs covered. • Rock-Solid Controls: Establish secure systems and ensure compliance with the latest financial reporting standards like GAAP and IFRS. • Innovative Strategies: Beyond the numbers, we offer strategic insights about market tren ds and help you make wise decisions. As we collectively pioneer a new era of financial reporting, Scrubbed is committed to bridging the gap between traditional accounting norms and the groundbreaking shifts introduced by the FASB on Crypto Assets. Our Technical Accounting Group is ready to assist your business in decoding the digital ledger, ensuring effective operations, and maintaining compliance with evolving regulations. We also provide specialized biotech accounting services, supporting organizations in highly regulated industries with tailored financial reporting solutions. For a comprehensive consultancy assessment tailored to your specific needs, reach out to [email protected].

Read More >
Blogs

The ESG Translation Gap: Why Good Accounting Data Fails Sustainability Audits

The ESG Translation Gap: Why Good Accounting Data Fails Sustainability Audits

If I had to name the first common mistake I see growing companies make when they tackle ESG reporting, it is foundational: They don’t know if the data they are using is complete and accurate. More than that, they often don’t even know if it is the data they should be using. For years, ESG reporting was largely voluntary, a way to answer the public’s demand for accountability and show investors you were responsible. But as optional guidelines transition into emerging laws and requirements, the landscape shifts. Investors and regulators no longer want marketing campaigns. They want accurate data provided with assurance. This brings us to a harsh reality I share with teams newly subject to these regulations: If you are required to file a report in 2027 based on 2026 data, and you wait until 2026 to start preparing, you are already late. Leaders often assume their existing accounting systems are naturally ready to handle ESG reporting. They almost never are. The Illusion of Alignment I see leadership teams fall into this trap constantly. They look at their organizational chart, see a separate Finance team and a separate ESG team, and assume they are covered. But in practice, these two teams are working in silos, speaking entirely different languages. I see this pattern constantly with companies that have been publishing ESG reports voluntarily for a number of years. As they prepare for mandated regulatory reporting, leadership feels secure because their ESG team is getting the exact reports they requested from Finance. But the moment you dig into the architecture and bridge the two teams, the gaps become obvious. Here is how the breakdown usually happens: The Ask: The ESG team needs data to calculate emissions, so they ask Finance for certain reports. The Hand-off: Finance, wanting to be helpful, pulls the data and hands it over. The Gap: Finance teams are wired to be compliant with accounting standards, but they aren’t trained to understand ESG reporting. ESG teams are great at translating finance data into emissions, but they don’t have the concept of an audit. Because the ESG team didn’t have an audit background, they didn’t know how to establish completeness and accuracy. They didn’t know how to look for certain accounting transactions that would otherwise be considered emission or non-emissive (i.e., advance or duplicate payments, reversed entries in the vendor reports). They were running calculations on raw data. The people didn’t fail: the structure simply wasn’t built to translate between the two departments. The Reality of Retroactive Cleanup The true operational complexity of ESG reporting reveals itself when you try to force accounting data into sustainability buckets. Take something as standard as a growing portfolio of leased facilities. From a purely financial perspective, a company might have these perfectly recorded. But you cannot translate that 1:1 to ESG data. For ESG, you have to review the business structure to see who actually holds ‘operational control’ so you can assign those facilities to the proper emissions categories.. When a company’s data architecture isn’t set up for this level of granularity, teams are forced to go back and manually revisit hundreds of outstanding contracts. What should take a minute to encode upfront easily turns into a multi-month project just to find the proper data sources. When you wait to build the system, you force your teams to look backward instead of forward. What You Need to Check Today The fix is actively bridging the technical gap. You need professionals who can translate complex sustainability metrics into an accounting standard, and vice versa. If you are a CFO or sustainability leader reading this today, before making your next public ESG commitment, take a hard look at your architecture. Ask yourself these three questions: Are my on-book activities scoped properly? Check if all financial transactions have been mapped to the appropriate ESG requirement. Are my off-book activities accounted for? Ensure your people management, technology, and operational data are fully captured. Are all stakeholders involved? If ESG reporting is falling entirely on your Finance team, or solely on your ESG team without Finance’s oversight, you have a translation gap. Operations, HR, and Tech must understand the why and the how of the data they are providing. A calm, predictable reporting cycle is designed, never improvised. Build the data architecture a year or two before the regulations hit, and ensure your financial execution naturally supports confident sustainability reporting.

Read More >

Contact Information

SF Bay Area Headquarters
111 Anza Boulevard, Suite 320, Burlingame, CA 94010, United States

Phone: (800)837-5160
Email: [email protected]

"Scrubbed" is the brand name under which Scrubbed Advisory, LLC and Scrubbed Assurance, LLP provide professional services. Scrubbed Advisory, LLC and Scrubbed Assurance, LLP practice in an alternative practice structure in accordance with the AICPA Code of Professional Conduct and applicable law, regulations, and professional standards. Scrubbed Assurance, LLP is a licensed independent CPA firm that provides attest services to its clients, and Scrubbed Advisory, LLC provides tax, finance, and support services to its clients. Scrubbed Advisory, LLC is not a licensed CPA firm.

Copyright © Scrubbed. All rights reserved.